The Spread Squeeze: Navigating CRE Risk Premiums in California
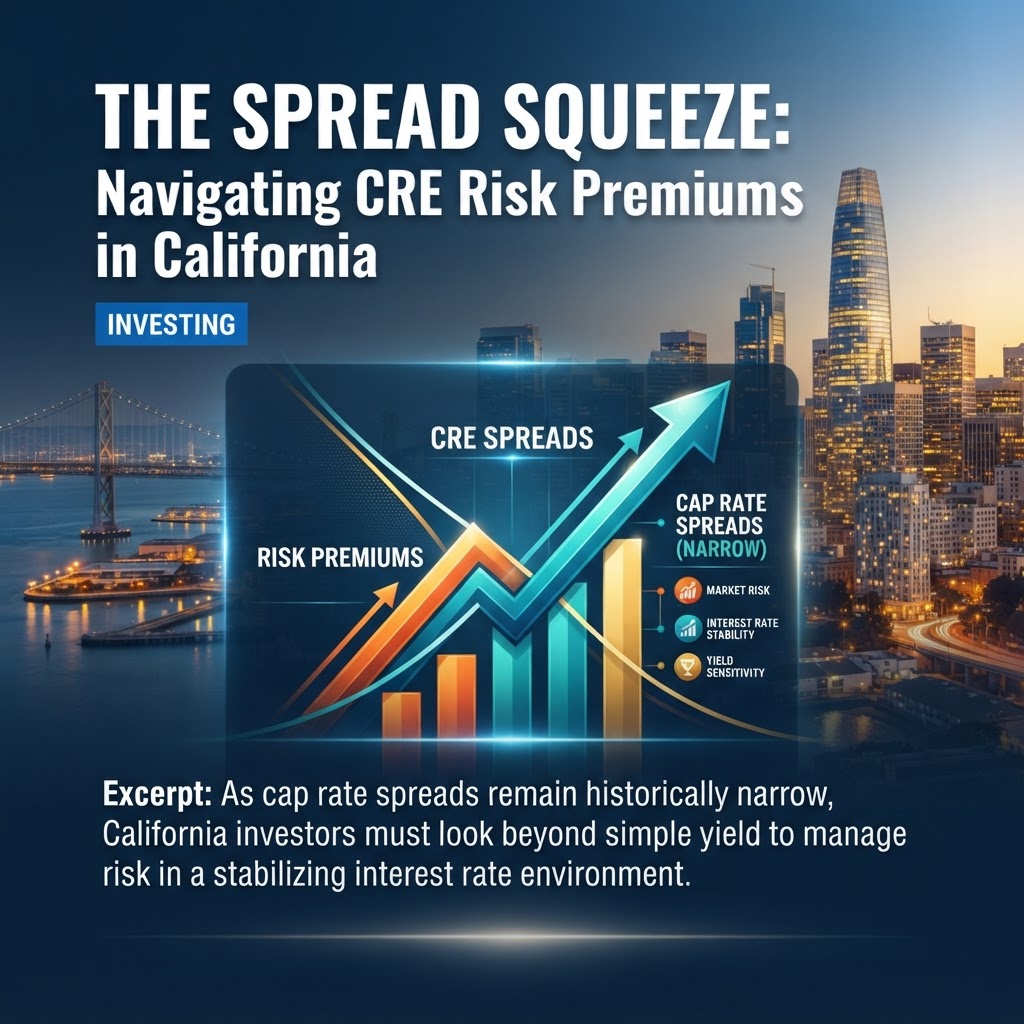
For the past four years, commercial real estate (CRE) investors have been locked in a high-stakes game of adjustment. As of October 2026, the market is no longer defined by the shock of rising rates, but by the persistent challenge of historically narrow cap rate spreads. With the 10-year Treasury yield hovering near 4.28%, the traditional risk premium—the extra return investors demand for the illiquidity and operational complexity of real estate—has compressed significantly compared to historical norms.
The Anatomy of the Spread
Historically, investors relied on a wider buffer between risk-free Treasury yields and CRE cap rates to justify acquisitions. Today, that buffer is thin. According to recent market data, cap rates for multifamily assets are averaging 5.5%, while retail sits at 6.2% and office at 6.8%. When compared to the 10-year Treasury, these spreads are razor-thin, leaving little room for error in underwriting.
This environment forces a shift in strategy. Investors can no longer rely on cap rate compression to drive returns. Instead, the focus has moved toward operational alpha and the ability to force appreciation through active management, particularly in supply-constrained California markets.
California's Bifurcated Reality
California remains a unique case study in the current cycle. While office assets continue to face structural headwinds—exacerbated by $289.2 billion in national office loan maturities through 2028—the state’s housing shortage continues to provide a floor for multifamily valuations. Data from the Summer 2026 Allen Matkins/UCLA Anderson Forecast indicates that a majority of respondents expect multifamily demand to outpace supply over the next three years, providing a defensive moat for investors in that sector.
However, the industrial sector remains the crown jewel of California’s diversified demand profile. With lender appetite remaining high for industrial assets, the sector continues to command premium interest, even as developers grow increasingly selective about new project starts.
Practical Takeaways for Investors
- Prioritize Operational Efficiency: In a low-spread environment, your return is generated by the property's net operating income (NOI), not market-wide cap rate compression. Focus on assets where you can actively reduce expenses or drive revenue through targeted capital improvements.
- Monitor Loan Maturity Walls: With significant office loan maturities looming, keep a close watch on distressed assets in urban cores. While the risk is high, well-located, amenity-rich office properties may offer entry points at valuations significantly below replacement cost.
- Leverage Data-Driven Underwriting: Given the volatility in the lending environment, rely on current SOFR-based benchmarks rather than historical averages. Current bridge financing structures, often featuring 24-month interest-only periods, require a clear exit strategy or stabilization plan before the maturity date.
- Focus on Supply-Constrained Markets: California’s regulatory environment, while challenging, acts as a barrier to entry that protects existing assets from oversupply. Prioritize submarkets where entitlement processes are rigorous, as these areas are less likely to see a sudden influx of competing inventory.
As we move into the final quarter of 2026, the "wait and see" approach is losing its utility. The market is stabilizing, but the era of easy leverage is over. Success today requires a disciplined focus on the spread, a deep understanding of local supply dynamics, and the operational expertise to extract value from every square foot.