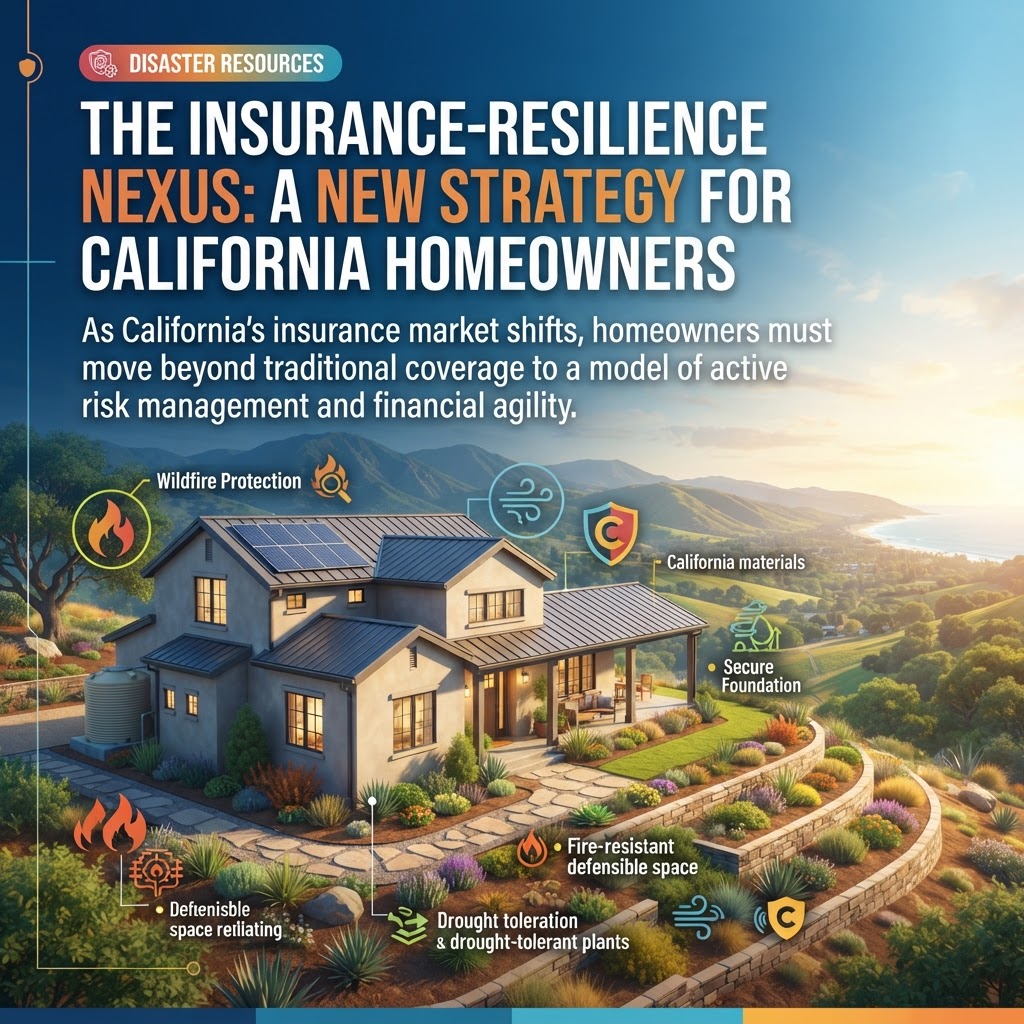
The Insurance-Resilience Nexus: A New Strategy for California Homeowners
For California homeowners, the traditional model of 'set it and forget it' property insurance is obsolete. With average premiums surging 84% since 2020 and major carriers scaling back coverage, the state's insurance landscape has entered a period of profound volatility. As of late 2026, the California FAIR Plan—the state's insurer of last resort—now covers nearly $700 billion in property, a 317% increase from 2021 levels. This shift necessitates a new, proactive approach to homeownership that prioritizes structural resilience as a financial imperative.
The Shift Toward Active Risk Management
The current market crisis is driven by a combination of climate-related risks and regulatory adjustments. The California Department of Insurance is now allowing carriers to incorporate forward-looking climate models into their pricing, which will likely lead to further premium adjustments. For the homeowner, this means that property insurance is no longer just a passive expense; it is a reflection of the home's physical vulnerability.
Homeowners should view property hardening—such as installing ember-resistant vents, clearing defensible space, and upgrading to fire-rated roofing—not merely as safety measures, but as essential tools for maintaining insurability. Some emerging insurance programs are beginning to integrate active wildfire risk management, combining standard coverage with maintenance plans that directly lower a property's risk profile.
Financial Agility in an Uncertain Market
With more than 1 in 5 California homeowners currently facing challenges with coverage, financial planning must account for the 'insurance gap.' Practical steps for homeowners and investors include:
- Audit Your Coverage: Do not wait for a non-renewal notice. Regularly review your policy to ensure it reflects current replacement costs, which have risen significantly due to inflation and labor shortages.
- Leverage State Protections: Familiarize yourself with the California LifeLine program, which recently expanded disaster relief protections to ensure that low-income residents maintain essential communication services during emergencies.
- Explore Mitigation Credits: As the market evolves, advocate for or seek out policies that offer premium credits for verified home hardening. Reducing your risk profile is the most effective way to combat rising costs in the long term.
The Resilience Mandate
California remains a high-risk environment, ranking fifth in total FEMA disaster assistance since 2000 with $25.2 billion in aid. While policymakers debate long-term solutions—ranging from public insurance programs to fossil fuel-funded bailouts—the individual homeowner's best defense remains physical and financial preparedness. By treating home hardening as a core component of property maintenance and staying informed on the evolving regulatory environment, homeowners can better navigate the current crisis and protect their most significant asset.


