Beyond the Foundation: Financial and Structural Readiness for California Homes
California consistently ranks among the nation’s top states for natural disaster risk, with recent data placing it third highest in the country for overall exposure. For homeowners, this reality necessitates a shift from reactive measures to a proactive, multi-layered strategy that addresses both physical property integrity and financial liquidity.
The Financial Reality of Risk
While many homeowners focus on physical hardening, the financial aftermath of a disaster is often the most overlooked vulnerability. With California ranking fourth in insurance losses per person, the gap between standard policy coverage and actual recovery costs is widening. A critical misconception remains that standard homeowners insurance covers earthquake damage; in reality, this requires separate policies through the California Earthquake Authority (CEA) or private insurers. Furthermore, even with coverage, high deductibles can lead to six-figure out-of-pocket expenses. Experts recommend maintaining a dedicated cash reserve of at least $1,000 in an accessible, physical location, as electronic payment systems may be incapacitated during regional infrastructure failures.
Structural Resilience and Tax Relief
Mitigation is the most effective tool for long-term insurance affordability. Initiatives like the California Safe Homes Act (AB 888) underscore the state's commitment to incentivizing property-level hardening. Homeowners should prioritize:
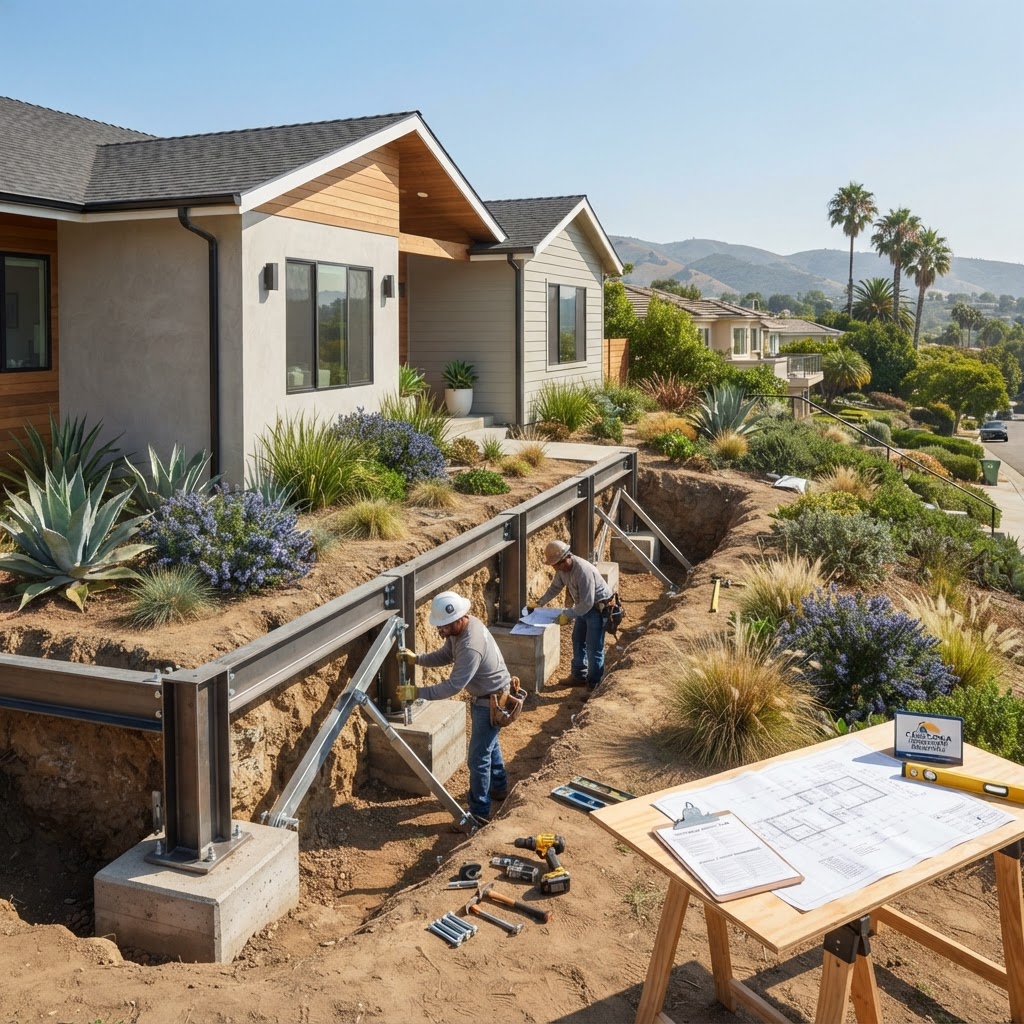
- Seismic Retrofitting: Securing the structure to the foundation to mitigate the high probability of significant seismic events in regions like the Bay Area, where there is a 63% chance of a magnitude 6.7 or larger earthquake in the next 30 years.
- Documentation: Maintaining a comprehensive, digital and physical inventory of property assets. This is essential for insurance claims and for qualifying for disaster relief programs.
- Tax Assessment Appeals: Property owners should be aware of disaster relief provisions through the State Board of Equalization. If a property sustains damage exceeding 50% of its full cash value, owners may be eligible for property tax relief, providing vital liquidity during the recovery phase.
Practical Takeaways for Owners and Investors
To build true resilience, homeowners must move beyond basic emergency kits:
- Audit Your Policy: Review your declarations page annually. Understand your specific deductible structure and whether your coverage is based on replacement cost or actual cash value.
- Leverage State Resources: Utilize the Listos California campaign resources to develop a family emergency plan that accounts for local wildfire, flood, and seismic risks.
- Prioritize Mitigation: Invest in hardening measures that may qualify for future insurance premium discounts or state-sponsored mitigation grants.
By integrating these financial and structural safeguards, California homeowners can better navigate the state's evolving risk landscape, protecting both their physical assets and their long-term equity.