The Lifecycle of Resilience: Planning for California’s Perpetual Disaster Cycle
For California homeowners, the conversation surrounding disaster preparedness has historically been reactive—a scramble to secure documents and supplies as wildfire season approaches or earthquake warnings spike. However, as the state navigates a volatile climate and evolving insurance landscape in 2026, a shift toward a 'Lifecycle of Resilience' is necessary. This approach treats disaster readiness not as an event, but as a continuous property maintenance cycle.
The New Reality of Risk Management
Data from the U.S. Census Bureau and recent state climate reports indicate that California’s geographic risk profiles are becoming increasingly layered. It is no longer sufficient to prepare for a single threat; homeowners now face a 'compounding risk' environment where drought conditions exacerbate wildfire susceptibility, followed by atmospheric rivers that heighten landslide risks on denuded slopes.
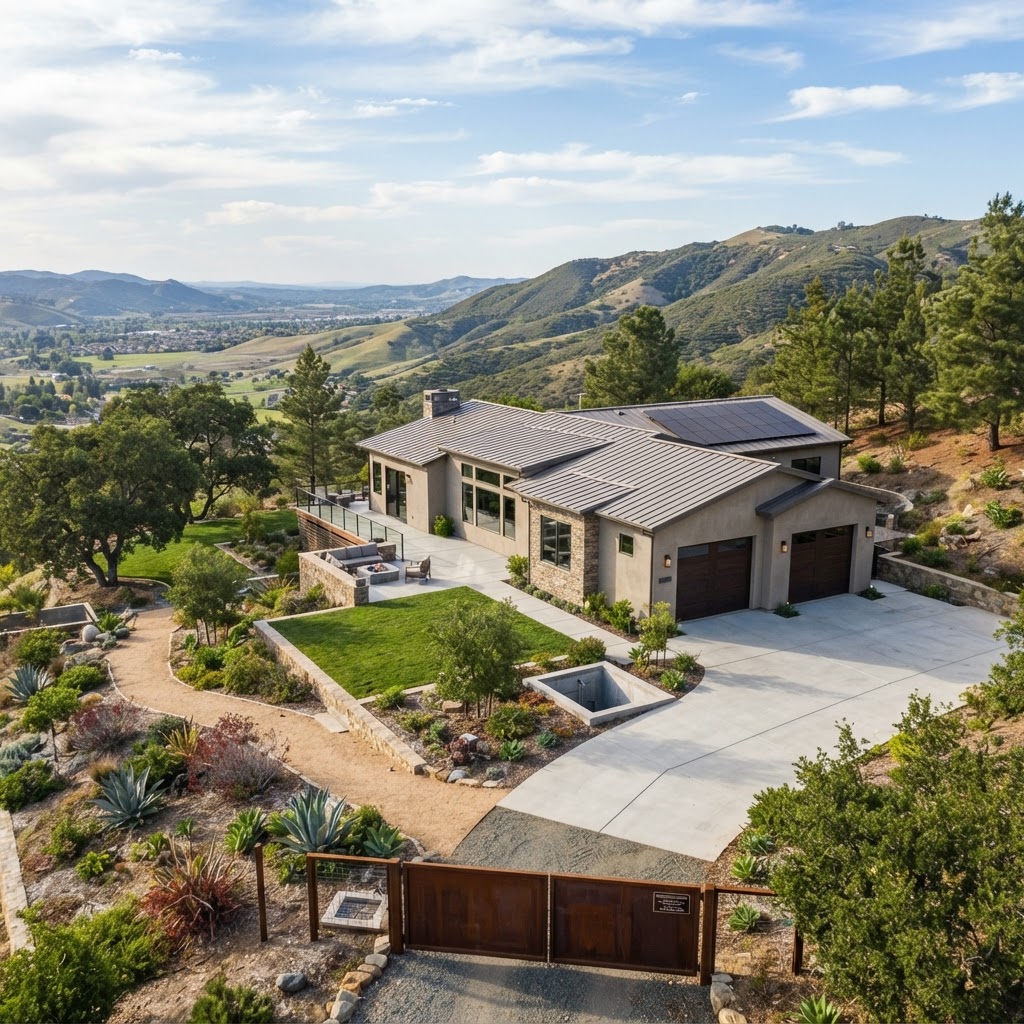
According to recent industry observations, properties that demonstrate ongoing investment in multi-hazard resilience—such as advanced drainage systems, fire-rated exterior materials, and seismic retrofitting—are showing greater stability in valuation and market liquidity compared to static properties. The goal is to move from 'surviving' the disaster to 'minimizing the recovery delta'—the gap between the property’s value before and after a disaster.
Integrating Resilience into Property Maintenance
To institutionalize disaster preparedness, homeowners should align resilience tasks with their existing home maintenance schedule:
- Seasonal Hardening: Rather than annual cleanups, integrate 'defensible space' audits into quarterly landscaping contracts. Clear vegetation, inspect ember-resistant vents, and ensure drainage paths are unobstructed before the rainy season.
- Documentation Audits: Treat your digital home inventory like a financial statement. Update records of home improvements, capital expenditures, and digital receipts annually. This documentation is critical for insurance claims and proving the 'basis' of your property for tax purposes after a loss.
- Seismic Health Checks: Given the age of much of California’s housing stock, ensure structural connections—particularly cripple walls and sill plates—are inspected every five years by a licensed professional, regardless of recent seismic activity.
Insurance and the Financial Baseline
The California insurance market has undergone significant restructuring. For homeowners, this means that the premium is only one part of the cost equation. The 'financial baseline' of your home now includes the cost of mitigation credits. Engage with your insurer to understand which home hardening actions qualify for premium discounts under the 'Safer from Wildfires' framework. Often, the ROI of a $2,000 mitigation project is realized not just in reduced premiums, but in the peace of mind that the property remains insurable in a tightening market.
Actionable Takeaways for Stakeholders
- For Sellers: Prepare a 'Resilience Disclosure Package.' Similar to a home inspection, providing evidence of seismic retrofitting, fire-resistant roof certifications, and drainage upgrades signals a well-maintained asset to potential buyers.
- For Investors: Evaluate potential acquisitions based on their 'Adaptive Capacity.' Can the property be easily retrofitted with modern fire-suppression or water-mitigation systems? Focus on assets where resilience can be tiered over several years.
- For Buyers: Incorporate a 'Disaster Audit' into your due diligence period. Use state-provided hazard mapping tools to understand not just the immediate risk, but the long-term maintenance implications of the property’s topography and location.
By transitioning disaster preparedness into a standard property maintenance lifestyle, California homeowners can mitigate the physical and financial volatility inherent in the state’s landscape. Resilience is not a final state of being; it is a permanent commitment to the endurance of your investment.


