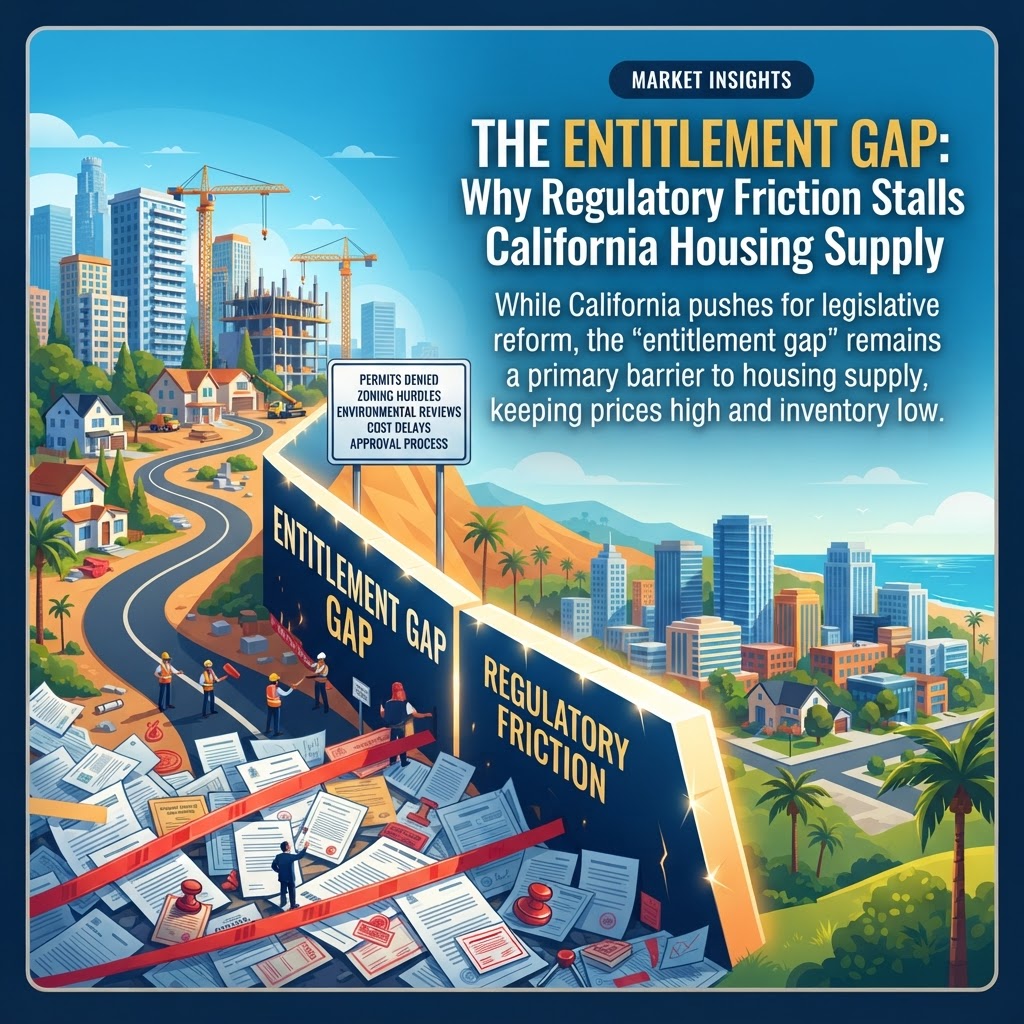
Entering late 2026, California’s commercial and residential investment real estate is navigating a unique set of regulatory constraints. While statewide median home prices hover around $904,640 (ManageCasa) and active inventory remains structurally tight at approximately 106,530 listings (Redfin), the narrative driving commercial and multi-unit capital is not solely about supply constraints or top-line home values. Instead, it centers on transaction and operational friction: navigating local transfer tax cliffs alongside statutory rent control boundaries.
The Dual Friction Trap: Measure ULA and Policy Hurdles
In major metro areas such as Los Angeles, transfer taxes like Measure ULA impose significant hurdles at key transaction thresholds: a 4% transfer tax starting at the $5 million threshold and rising to 5.5% at or above $10 million (AllView Real Estate). Because Measure ULA applies broadly to commercial real estate, multi-family properties, and mixed-use assets rather than just high-end single-family homes, it creates distinct deal friction around the $5 million valuation line.
Simultaneously, the regulatory layer under the Tenant Protection Act (AB 1482) caps annual rent growth across covered portfolios to 5% plus the regional Consumer Price Index (CPI), or 10%, whichever is lower. Together, these measures narrow the margin for traditional value-add renovations in rent-controlled assets, demanding higher operational efficiency and precise exit modeling.
The Valuation Chasm and Strategic Adjustments
The friction surrounding transaction taxes has introduced visible behavioral shifts among commercial brokers and institutional underwriters:
- Pricing Around the Cliff: Sellers of multi-family buildings historically assessed between $5.0 million and $5.3 million frequently face price renegotiations to keep gross transactions under the $5 million boundary, as a 4% levy on total gross consideration can erode expected net proceeds.
- The Rolling 15-Year Exemption Filter: Institutional buyers seeking core and core-plus residential exposure are prioritizing newer construction built within the last 15 years, qualifying for exemption from AB 1482's operational caps (AllView Real Estate).
- Capital Diversification Across Municipalities: Capital seeking Southern California multi-family exposure is increasingly balancing acquisitions across surrounding municipalities in Orange, San Diego, and Ventura counties that do not levy comparable high-threshold transfer taxes.
Actionable Strategies for Investors and Operators
In this policy landscape, executing transactions requires disciplined underwriting and operations:
- Underwrite Exit Caps with Local Taxes Factored In: Underwriting models should factor local gross receipts and transfer taxes into terminal capitalization rates and exit cost assumptions rather than relying on standard disposition percentages.
- Target Unincorporated and Independent Jurisdictions: Investors evaluating residential income properties across Southern California can identify submarkets within adjacent municipal borders where local tax rates adhere closer to the statewide base.
- Rigorous Expense Tracking: With coastal rental vacancies holding under 5% (ManageCasa), maintaining net operating income hinges on managing operating expenses, including insurance compliance, mandatory balcony/structural checks (e.g., SB 326), and administrative overhead.
As California's market matures through the second half of 2026, long-term capital allocation will favor operators who understand local municipal boundaries and manage asset cash flows through strict regulatory and operational discipline.