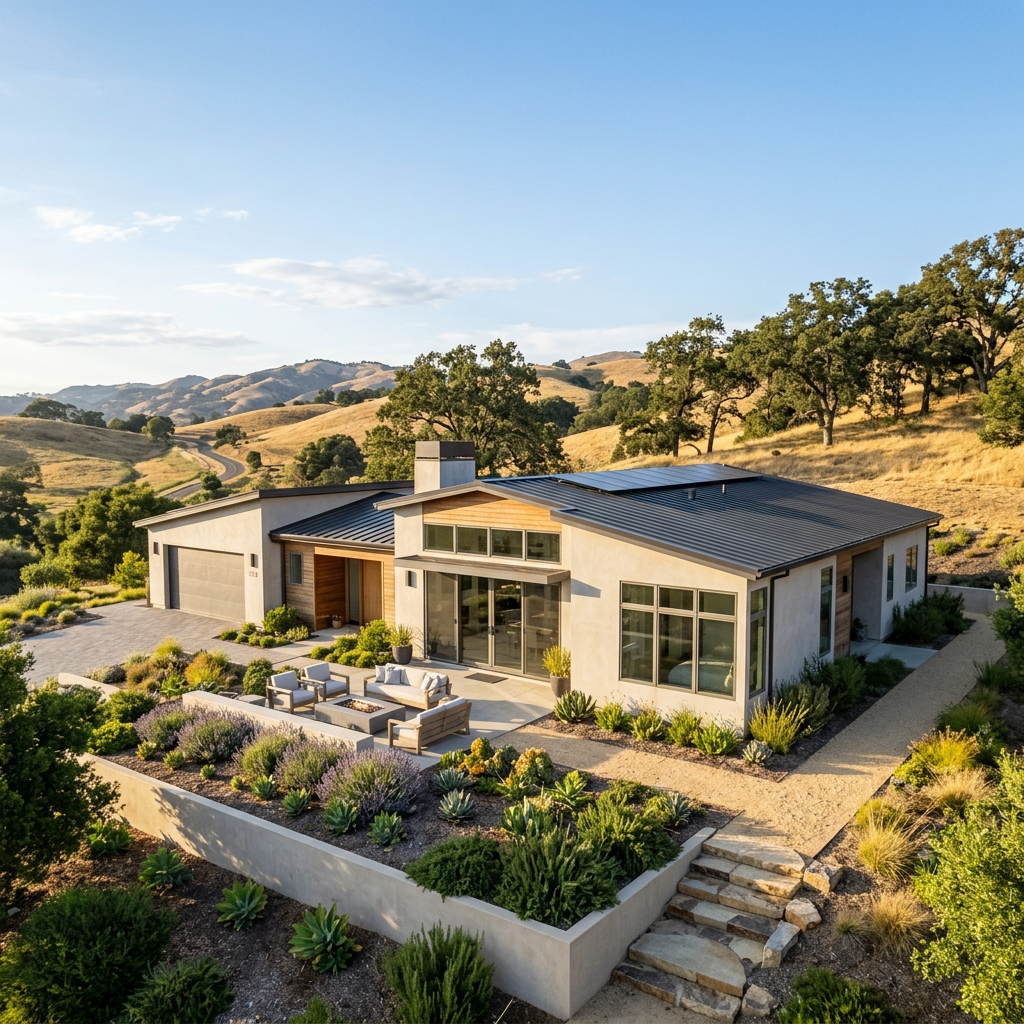
The Convergence of Risk and Real Estate Value
As of March 2026, California homeowners face a unique dual challenge: increasing climate-driven risks and a complex, hardening insurance market. For the modern homeowner, disaster preparedness is no longer just about a 'go-bag'; it is a fundamental strategy for protecting property value and ensuring long-term marketability. Data from the 2025 California Department of Insurance reports indicate that non-renewal rates in high-risk zones have remained volatile, making physical resilience a prerequisite for affordable coverage.
The Insurance Crisis and the FAIR Plan
The primary hurdle for many California property owners is securing comprehensive coverage. With several major national carriers restricting new policies in the state, the California FAIR Plan has seen record enrollment. However, the FAIR Plan is a 'last resort' and only covers fire. To protect equity, homeowners should consider 'Difference in Conditions' (DIC) policies to fill gaps in liability and water damage. Practical Takeaway: Investors and buyers should include a 14-day insurance contingency in all contracts to ensure a property is insurable before closing escrow.
Wildfire Mitigation: Beyond Defensible Space
Assembly Bill 38 (AB 38) has fundamentally changed the selling process in California. Sellers in high fire hazard severity zones must now provide documentation of compliance with defensible space requirements. To enhance resilience and lower insurance premiums, focus on 'home hardening':
- Ember-Resistant Zones: Create a five-foot non-combustible perimeter around the structure using gravel or stone instead of mulch.
- Vents: Upgrade to ember-resistant vents (ASTM E2886 rated) to prevent wind-blown embers from entering attics or crawlspaces.
- Glazing: Install multi-paned, tempered glass windows which are significantly less likely to shatter under heat stress.
Seismic Resilience and the ROI of Retrofitting
While wildfires dominate the news, seismic risk remains a constant for the California market. According to the California Earthquake Authority (CEA), older 'crawlspace' homes built before 1980 are particularly vulnerable to sliding off their foundations. The 'Brace + Bolt' program offers grants of up to $3,000 for qualifying homeowners to seismically retrofit their properties. Data Point: Homes that have undergone seismic retrofitting often see a reduction in CEA insurance premiums of up to 25%, providing a direct return on investment while securing the structure's integrity.
Strategic Resources for Resilience
Navigating these risks requires utilizing state-level data tools to assess a property's specific vulnerability profile:
- Cal Fire’s Fire Hazard Severity Zone Maps: Essential for understanding the regulatory requirements for a specific parcel.
- MyHazards (Cal OES): An interactive tool that identifies risks for earthquakes, floods, and tsunamis based on address.
- Homeowners’ Associations (HOAs): Many California HOAs are now pursuing 'Firewise USA' recognition, which can lead to community-wide insurance discounts.
Conclusion: The Resilience Premium
In the 2026 real estate landscape, the most resilient homes will command a premium. Buyers are increasingly scrutinizing 'hardened' features and insurance history. By proactively investing in seismic bracing, ember-resistant materials, and proper insurance layering, California homeowners can mitigate risk while fortifying their most significant financial asset.


