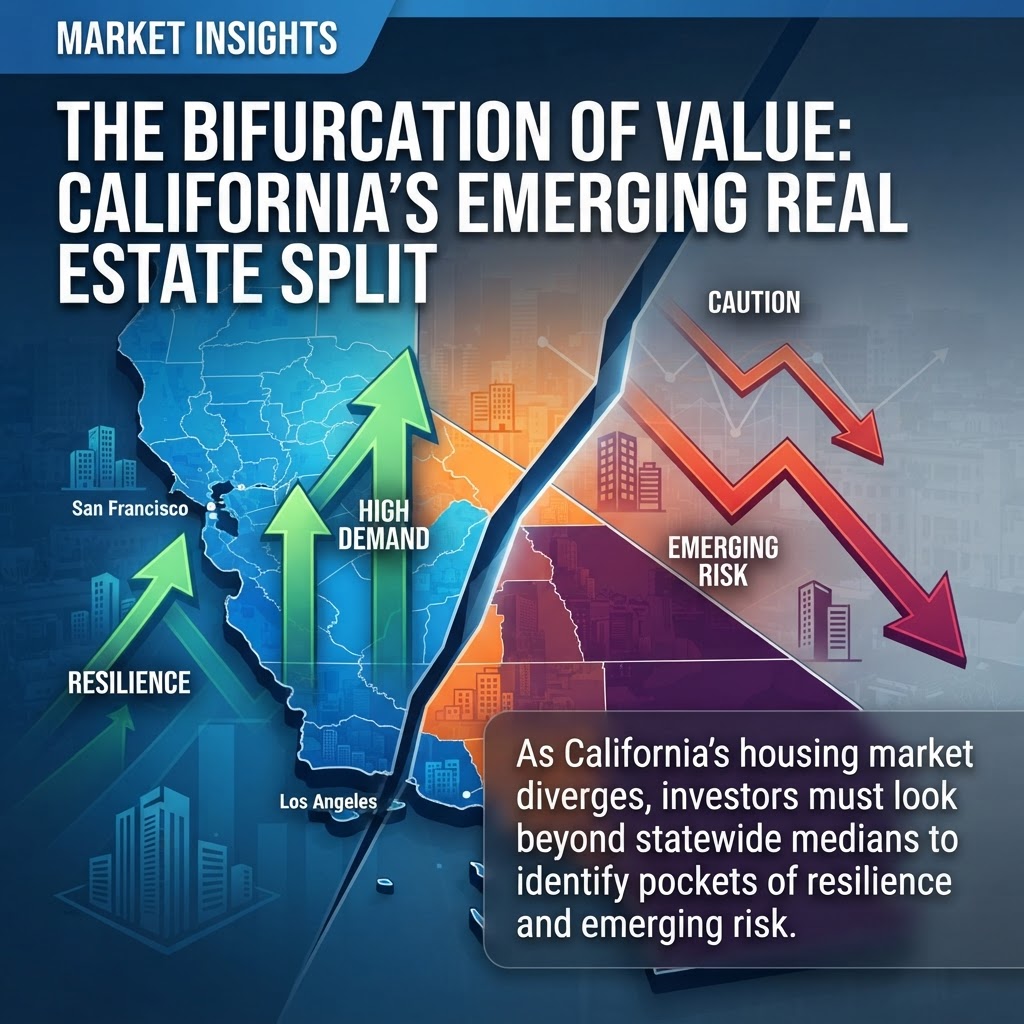
The Bifurcation of Value: California’s Emerging Real Estate Split
The California housing market is no longer moving in a singular direction. While statewide data from the California Association of Realtors (C.A.R.) shows a 6.5% year-over-year decline in existing single-family home sales as of September 2026, the aggregate numbers mask a profound divergence in regional performance and asset-class behavior. For investors and market participants, the era of 'rising tides lifting all boats' has been replaced by a landscape defined by extreme micro-market volatility.
The End of Regional Lockstep
Recent data highlights a stark contrast in how different metros are absorbing the pressure of mortgage rates hovering near 7%. While San Francisco has defied national trends with significant price appreciation, other hubs like San Jose and San Diego have experienced sharp cooling. This suggests that local economic drivers—specifically the concentration of industry-specific employment and inventory constraints—are now more influential than broad macroeconomic policy.
The Million-Dollar Floor
Despite the cooling in transaction volume, the statewide median price remains resilient, hovering near $900,000. This is largely driven by a shift in the composition of sales; million-dollar homes accounted for 35.9% of transactions in September 2026. This 'price floor' effect is not necessarily evidence of broad appreciation, but rather a reflection of the fact that lower-tier inventory remains locked by the mortgage rate-lock effect, leaving only higher-end, less rate-sensitive properties to drive the median.
Practical Takeaways for Market Participants
- For Investors: The Central Valley and Sacramento continue to offer superior entry economics compared to coastal metros. With sales volume in these regions showing relative strength, they remain the primary targets for those seeking cash-flow potential rather than pure appreciation.
- For Sellers: The 'days on market' metric is creeping upward, and the share of sales involving price reductions has hit record highs. Sellers must move away from 'aspirational pricing' and focus on property-specific financing incentives, such as offering to cover closing costs or facilitating rate buydowns, which are proving more effective than simple price cuts.
- For Buyers: With inventory nudging higher due to slower sales rather than new construction, buyers are gaining modest negotiating leverage. However, this is not a universal buyer's market. Success requires granular analysis of local inventory levels—specifically in the condo and townhome sectors, where unsold inventory indices are rising faster than in the single-family detached market.
The Path Forward
As we move toward 2027, the market is transitioning from a supply-constrained seller's market to a more complex environment where buyer caution is outpacing the owner's need to sell. Investors should prioritize markets with diverse economic bases and avoid areas where construction pipelines are stalling due to regulatory friction. By focusing on the 'bifurcation of value'—the gap between resilient, high-demand submarkets and those struggling with affordability—participants can navigate the current volatility with greater precision.