The Insurance-Construction Loop: Why CA Renovation Costs Are Skyrocketing
As of September 2026, the California real estate market is grappling with a feedback loop that is fundamentally altering how property value is maintained. While much of the industry focus remains on interest rates and inventory, a quiet, structural shift is occurring: the convergence of the wildfire insurance crisis and the rising cost of residential construction.
The Shift from New Builds to Hardening
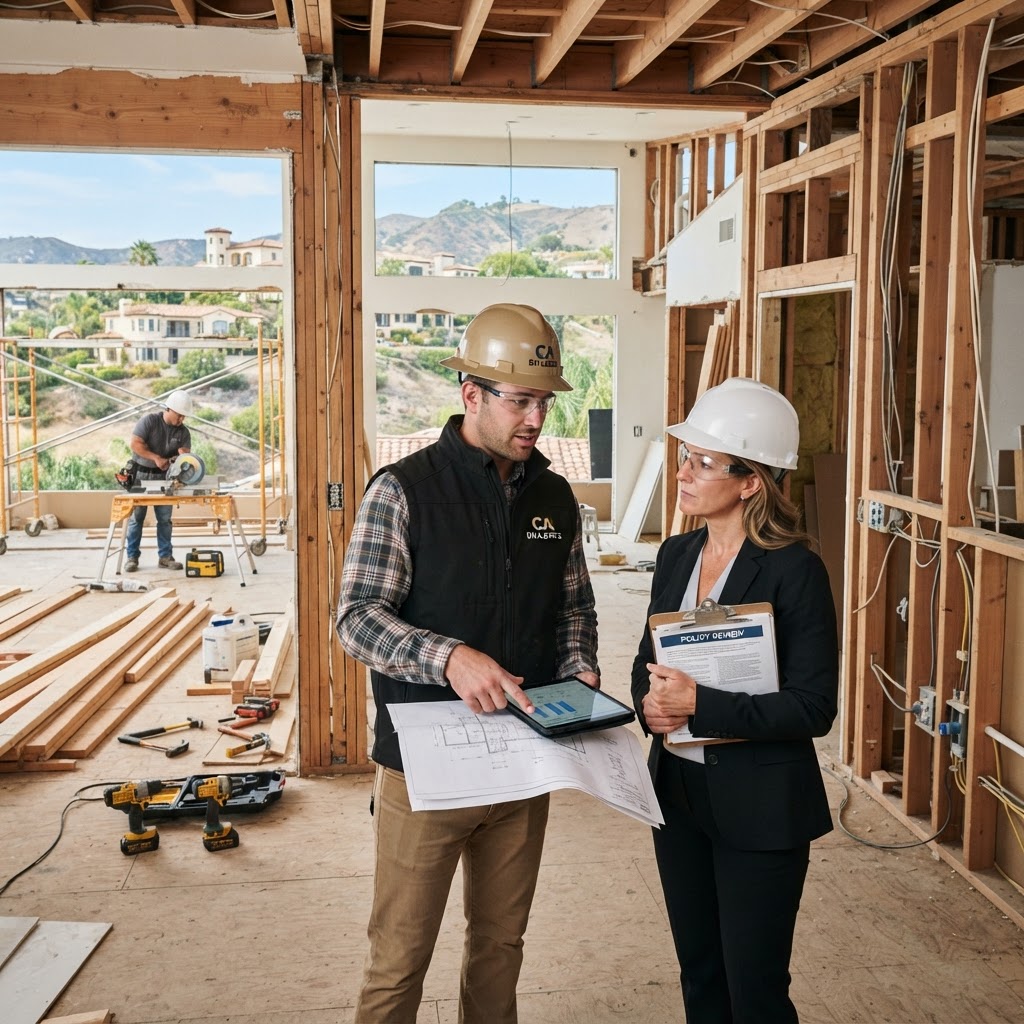
Data from the California Department of General Services indicates that the California Construction Cost Index (CCCI) has climbed steadily throughout the summer, reaching 10,717 by September 2026. Unlike previous cycles where growth was driven by new housing starts, the current momentum is fueled by a surge in renovation and retrofitting projects. Homeowners, facing prohibitive insurance premiums or outright policy cancellations, are increasingly prioritizing 'fire-hardening'—upgrading roofs, siding, and ventilation systems to meet stringent insurer requirements.
The Cost of Compliance
This pivot has created a localized inflation in construction labor and materials. Contractors are reporting that demand for specialized fire-resistant materials is outpacing supply, further exacerbated by labor shortages in the skilled trades. According to recent industry reports, residential construction spending is now heavily skewed toward these defensive renovations rather than expansion or new builds, as homeowners attempt to protect their existing equity in high-risk zones.
Practical Takeaways for Stakeholders
- For Homeowners: Before listing a property, conduct a 'hardening audit.' Properties with documented fire-resistant upgrades are seeing significantly higher interest and faster closing times, as buyers are increasingly wary of the insurance hurdles associated with older, non-compliant homes.
- For Investors: Look for opportunities in 'fix-and-flip' projects that focus on resilience. Properties that require significant insurance-mandated upgrades are often undervalued by sellers who lack the capital or patience to manage the renovation process.
- For Buyers: Factor insurance premiums into your debt-to-income ratio early. Do not rely on historical insurance costs; obtain a quote for the specific property address before finalizing your offer, as premiums can vary wildly based on local fire-risk modeling.
As the state navigates the ongoing insurance watchdog transition and legislative efforts to stabilize the market, the 'resilience premium' will likely remain a permanent fixture of California real estate. Investors and residents alike must recognize that in 2026, the most valuable home improvement is often the one that keeps the insurance policy active.