The Yield Curve Conundrum: Why Treasury Volatility Is Reshaping CA Lending
For California homebuyers, the mortgage landscape in September 2026 has become increasingly tethered to the volatility of the 10-year Treasury yield. While headlines often focus on the national average for 30-year fixed mortgages—which recently hovered near 6.76% according to Freddie Mac—the real story for Californians lies in the widening gap between bond market movements and local lending accessibility.
The Treasury-Mortgage Link
The 10-year Treasury yield has recently experienced significant upward pressure, with recent spikes pushing yields toward the 4.9% threshold. Because mortgage lenders price their loans based on the secondary market for mortgage-backed securities, which track closely with Treasury yields, this volatility creates an immediate ripple effect. When the 10-year yield jumps by even 5 to 10 basis points in a single day, lenders often adjust their rate sheets upward to mitigate risk, leaving buyers in high-cost states like California particularly vulnerable to sudden shifts in purchasing power.
Implications for the California Market
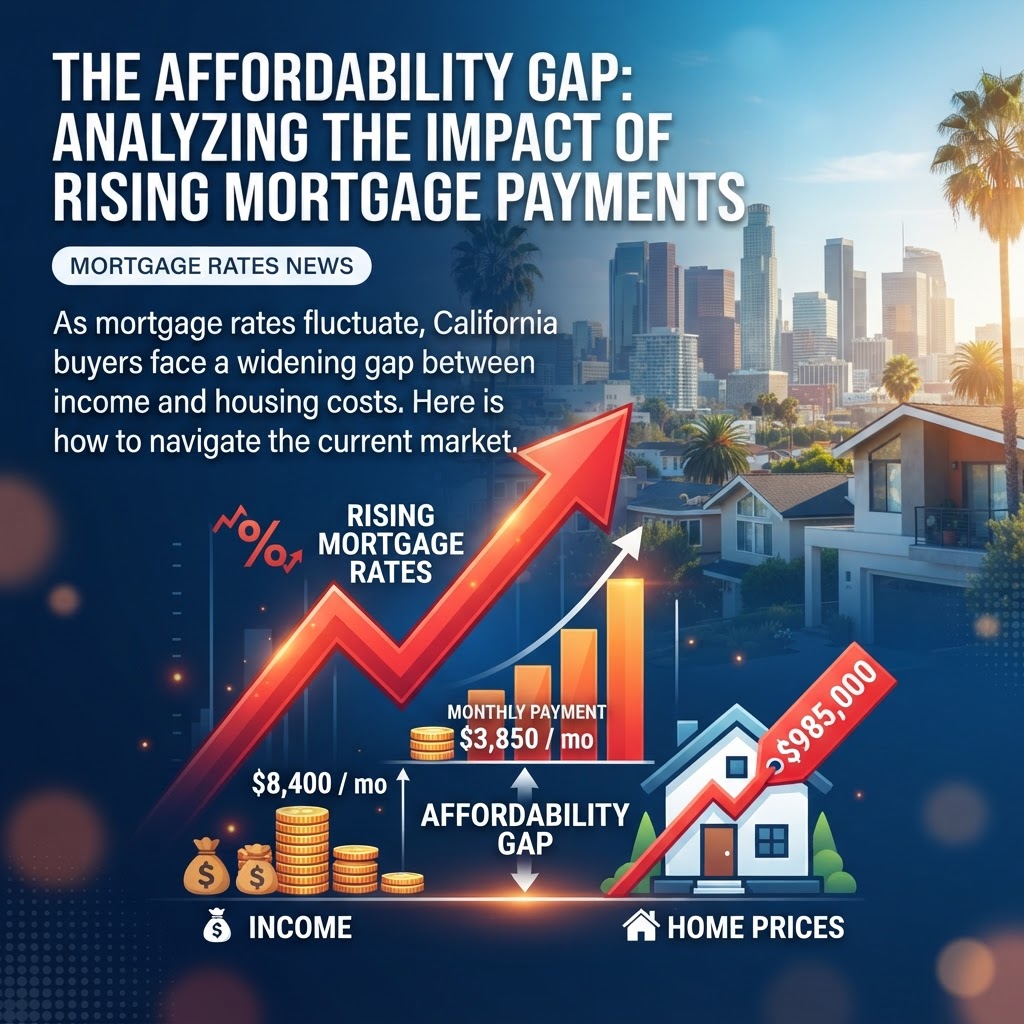
In California, where the average loan size often exceeds $500,000, even minor rate fluctuations have outsized impacts on monthly debt-to-income (DTI) ratios. As rates climb, the "conforming-jumbo" divide becomes a critical pressure point. Buyers who were previously qualified for conventional financing may find themselves pushed into jumbo territory or forced to reconsider their price points entirely as monthly payments swell.
Practical Takeaways for Market Participants
- Locking Strategy: In a volatile rate environment, waiting for a "better day" is increasingly risky. Buyers should prioritize lenders who offer "float-down" options, which allow for a rate reduction if market conditions improve after a lock is initiated.
- Focus on APR, Not Just Note Rate: With lenders adjusting pricing daily to account for Treasury volatility, the Annual Percentage Rate (APR) provides a more accurate picture of the total cost of borrowing, including points and fees that may be used to buy down the rate.
- Leverage Local Credit Unions: While national banks are often the first to adjust rates in response to Treasury movements, local California credit unions may have different portfolio lending guidelines that can provide more stability or competitive pricing for well-qualified borrowers.
- Review Debt-to-Income Ratios: Before entering the market, consult with a loan officer to stress-test your budget against a 7.25% rate. This buffer ensures that if the 10-year Treasury continues its upward trend, your financing remains viable.
As we move through the remainder of September, the primary indicator for California buyers remains the bond market. Monitoring the 10-year Treasury yield is no longer just for institutional investors; it is a necessary step for any Californian looking to navigate the current lending environment with confidence.