The Insurance Bottleneck Moves From the Hills to the Valley Floor
For years, the hazard insurance conversation in California real estate was largely isolated to the wildland-urban interface—canyons in Malibu, ridge lines in the Sierra foothills, and heavily wooded corridors across Northern California. However, as the fall 2026 transaction season gets underway, underwriting friction has decisively entered flatland suburbs and moderate-risk metros, reshaping deal velocity and mortgage qualification across the state.
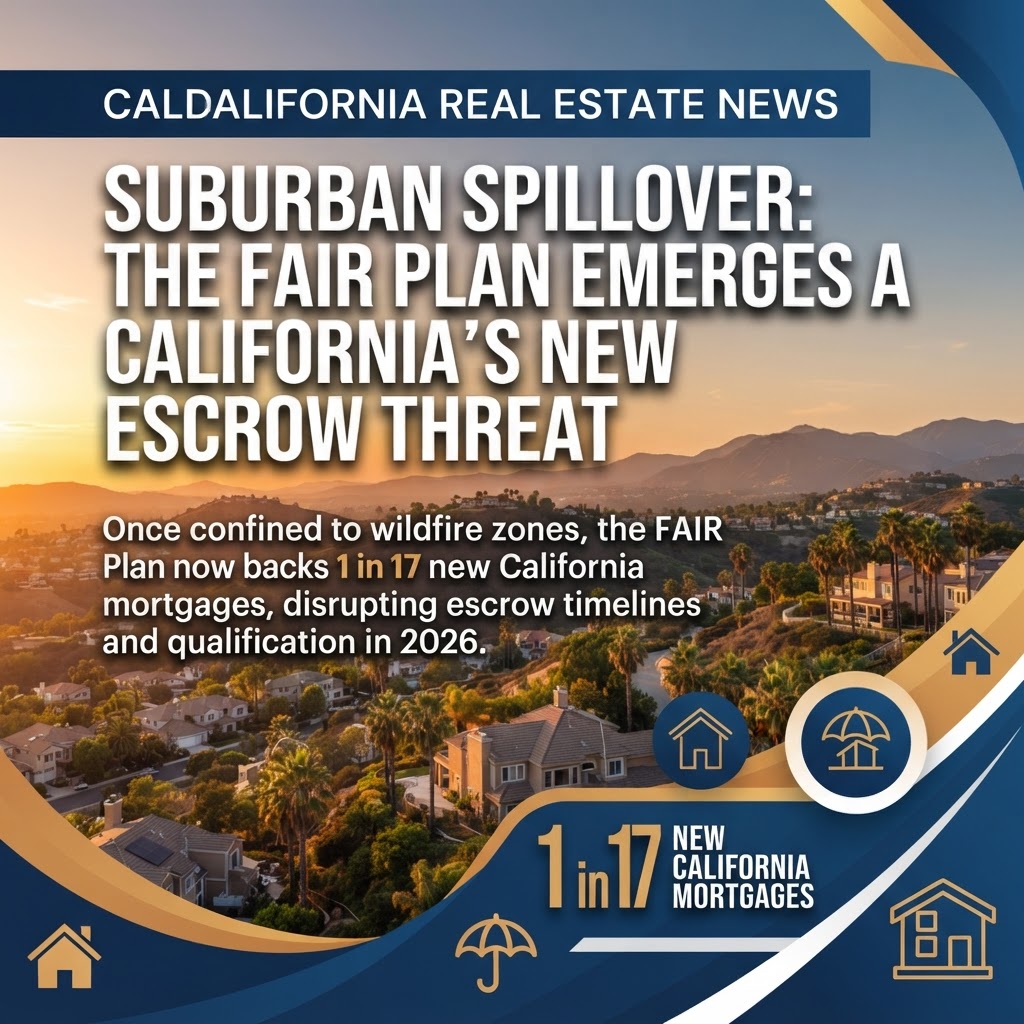
According to findings published by Stanford University’s Climate and Energy Policy Program (CEPP), average California homeowner insurance premiums surged by 84% between late 2020 and early 2026, while average deductibles rose from $1,813 to $2,553. More significantly for the transaction pipeline, the state-mandated insurer of last resort—the California Fair Access to Insurance Requirements (FAIR) Plan—now backs roughly 6% of all new single-family mortgage originations statewide, meaning more than one in every 17 new home loans relies on this backstop policy to cross the finish line.
The Dual-Policy Reality and Escrow Delays
The operational hurdle confronting today’s buyers and loan officers is that a standard FAIR Plan policy is not a comprehensive homeowners policy. By charter, it protects only against basic perils: fire, lightning, smoke, and internal explosion. It excludes water damage, liability, theft, and falling objects.
Because conventional lenders require standard comprehensive peril and liability coverage before issuing loan docs, an estimated 50% of FAIR Plan recipients are forced to secure a supplemental "Difference in Conditions" (DIC) companion policy from a private carrier. In practice, closing a transaction today frequently involves coordinating two separate policy binders, dual underwriting timelines, and double the administrative overhead.
Mortgage brokers across Southern California and the Central Valley report that insurance discovery, once a perfunctory checklist item completed 48 hours before closing, is now causing contract extensions and financing contingency disputes when annual quotes come in thousands of dollars above initial debt-to-income (DTI) underwriting thresholds.
Why Moderate-Risk ZIP Codes Are Feeling the Squeeze
The Stanford study highlights that FAIR Plan dependency is now showing up in moderate- and low-wildfire-risk ZIP codes at twice the rate of its overall market footprint. This migration is the delayed downstream effect of seven of the state’s 12 largest residential insurers curtailing or completely freezing new business over the past four years.
As primary carriers retrenched to reduce aggregate exposure under legacy Proposition 103 rate constraints, private availability thinned out in secondary suburban rings. Regulatory reforms by the California Department of Insurance designed to coax admitted carriers back into underserved areas—partially by allowing catastrophe modeling and reinsurance passthrough costs—are still filtering into consumer-facing availability. Until private capacity fully restabilizes, escrow officers and loan processors are left navigating a congested FAIR Plan application queue.
Strategic Action Items for Today’s Market Participants
With insurance conditions representing a pivotal deal hurdle in California's 2026 housing landscape, buyers, sellers, and investors must adjust their transaction timelines:
- Buyers: Clear the Insurance Contingency in Week One. Do not wait for appraisal sign-off to price insurance. Obtain written property binder estimates during the first five business days of escrow. If a FAIR Plan plus DIC wrapper is necessary, calculate the added annual premium immediately against front-end and back-end DTI limits.
- Sellers: Pre-Market the Property’s Insurability. Sellers should consider obtaining a preliminary insurability review or working with an independent brokerage to identify transferable or readily available admitted coverage before listing. Disclosing whether a property currently relies on FAIR Plan coverage manages buyer expectations and prevents last-minute financing fallouts.
- Dual-Track Your Policies: When acquiring property in fringe suburban or hillside adjacent tracts, request that your insurance broker initiate both an admitted carrier search and a backup FAIR Plan application simultaneously to avoid a 14-to-21-day escrow delay if admitted coverage is declined late in underwriting.
- Investors and Landlords: Model Capitalized Insurance Inflation. When calculating cap rates on single-family rentals or small multifamily assets, avoid using historical trailing-12 insurance figures. Stress-test underwriting models with an assumption of higher baseline premiums and larger reserve allocations for wind, fire, and liability riders.