The 2026 Inventory Paradox
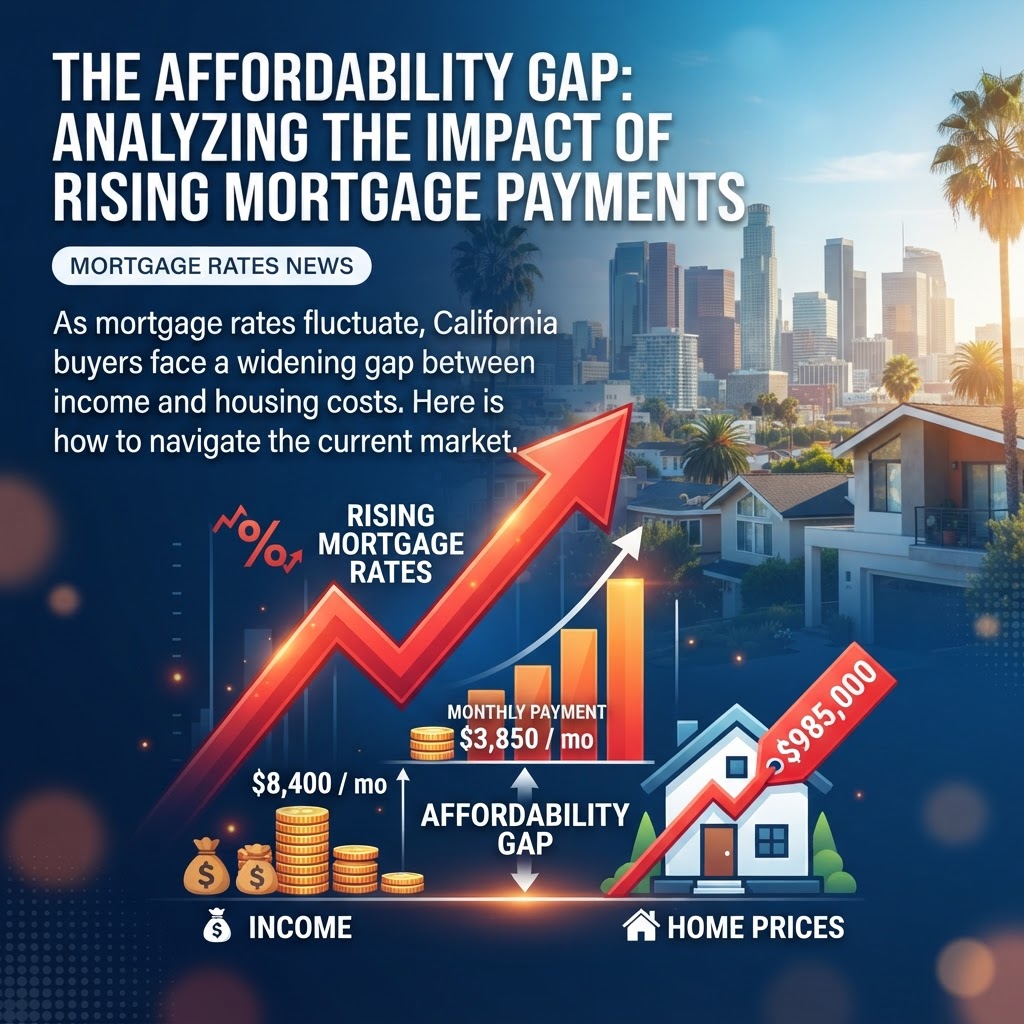
As of mid-May 2026, the California housing market faces a unique structural challenge. Despite mortgage rates stabilizing in the 6.4% to 6.7% range, the California Association of Realtors (CAR) reports that active listings remain 15% below pre-pandemic norms. For the Golden State’s move-up buyers, this creates a 'chicken-and-egg' dilemma: they cannot find a home to buy without a non-contingent offer, but they cannot make a non-contingent offer without liquidating the equity in their current residence.
In response, a sophisticated lending trend has emerged as the dominant strategy for the 2026 spring season: the institutional bridge-to-permanent pivot. Unlike the predatory bridge loans of decades past, today’s products are designed to bypass the 'contingency trap' that causes 40% of California contracts to fall through in competitive hubs like San Diego, Orange County, and the Bay Area.
How the 'Buy-First' Strategy Works in 2026
The modern bridge loan allows a homeowner to borrow against the equity of their current home to fund a down payment on a new property. This effectively turns a financed buyer into a 'pseudo-cash' buyer. In a market where the National Association of Realtors (NAR) indicates that 28% of all transactions are now all-cash, this liquidity is the only way for many California families to compete.
Key features of the current 2026 bridge landscape include:
- Cross-Collateralization: Lenders are increasingly looking at the total loan-to-value (LTV) across both the departure and the destination properties, often allowing for a single monthly payment during the transition period.
- Interest-Only Deferment: Many California-specific bridge products now offer six months of deferred interest, recognizing that high-end homes in markets like Los Gatos or Pasadena may take 60-90 days to close even in a hot market.
- The 75% Equity Rule: Lenders typically require at least 25% to 30% equity in the departure home to qualify for a bridge loan that covers both the down payment and closing costs of the new purchase.
The Math of the Pivot: Rates vs. Opportunity
While bridge loans carry higher interest rates—currently averaging 8.5% to 9.2%—the duration of the debt is the critical factor. For a California buyer purchasing a $1.2 million home, the cost of carrying a bridge loan for 90 days is often lower than the appreciation loss of waiting another year or the risk of losing a preferred property to a cash offer.
Furthermore, once the original home sells, the bridge loan is retired, and the remaining debt is converted into a traditional 30-year fixed or high-balance loan. Data from the Federal Reserve suggests that with inflation trending toward the 2% target, the 'permanent' portion of these loans may be eligible for a streamline refinance by mid-2027, making the current high-rate bridge a temporary bridge to long-term stability.
Practical Takeaways for California Buyers
- Audit Your Equity: Before shopping, get a professional valuation of your current home. You generally need a combined LTV of under 75% across both homes to utilize the most competitive bridge products.
- Secure the 'Exit Strategy' Early: Lenders will scrutinize the sellability of your current home. In 2026, homes with deferred maintenance are seeing longer days-on-market; consider a pre-sale renovation loan to ensure your 'bridge' doesn't become a 'pier.'
- Factor in the 'Convenience Premium': View the higher interest rate of the bridge loan as a transaction fee for the ability to move once rather than twice. In high-cost California markets, the cost of temporary housing and double-moving often exceeds the interest cost of a 90-day bridge.
As we move into the second half of 2026, the ability to decouple the purchase from the sale will remain the defining advantage for successful buyers in the California market.