The 2026 Liquidity Shift: Beyond the Traditional Bank
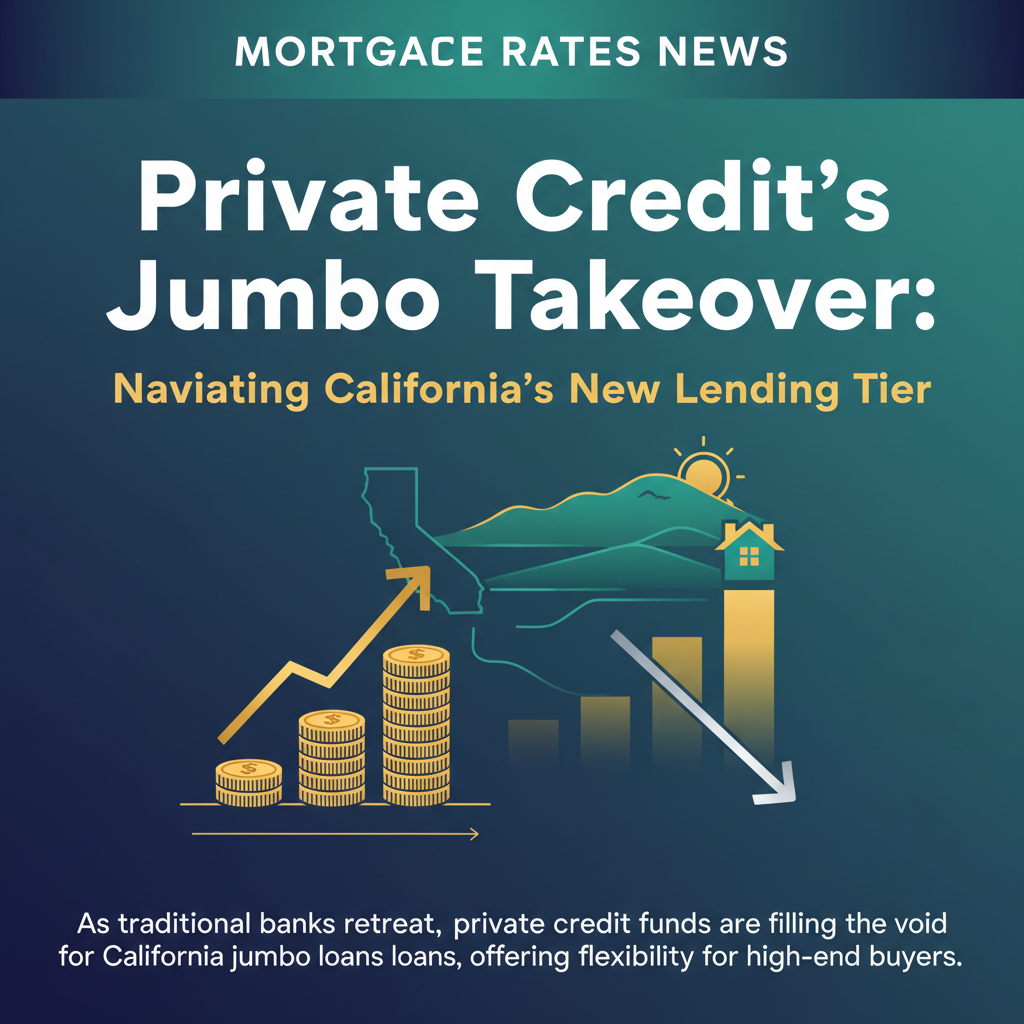
As of May 2026, the California mortgage landscape has reached a peculiar equilibrium. While the 30-year fixed rate has stabilized near 6.45%, a new challenge has emerged for the state’s high-end market: the retreat of traditional regional banks from the jumbo lending space. Following updated Basel III endgame capital requirements, many of the institutions that once dominated Silicon Valley and Coastal Southern California have tightened their balance sheets, leaving a liquidity gap in the non-conforming market.
The Rise of the Shadow Jumbo
Into this vacuum have stepped private credit funds and non-bank institutional lenders. Unlike the regional banks of the past decade, these private entities are not governed by the same stringent capital-to-asset ratios, allowing them to underwrite California’s unique property profiles with greater agility. In the current market, 'Private Credit Jumbos' now account for an estimated 22% of new originations for homes priced above $1.5 million in counties like Marin, San Diego, and Orange.
The Data: Jumbo vs. Conforming Spreads
According to recent data from the Mortgage Bankers Association and California Association of Realtors (CAR), the spread between a conforming loan and a jumbo loan has widened to 45 basis points—the largest gap seen since the 2023 banking tremors. For a California buyer seeking a $2 million mortgage, this translates to a meaningful difference in monthly carry. However, the trade-off is accessibility. While traditional banks are demanding 760+ FICO scores and 12 months of liquid reserves, private credit lenders are increasingly prioritizing asset-heavy profiles and 'common sense' underwriting for entrepreneurs whose tax returns don't tell the full story.
Strategic Takeaways for California Buyers
- Audit Your Asset Liquidity: Private credit lenders often look at 'post-closing liquidity' rather than just debt-to-income. Buyers should be prepared to show a comprehensive map of brokerage accounts and 401k balances to secure the best tiers.
- Factor in the 'Liquidity Premium': Expect to pay a slightly higher origination fee (often 0.5% higher than a standard agency loan) in exchange for the ability to close on complex properties or non-traditional income streams.
- Bridge to Re-Fi: Many of these private credit products are structured as 5 or 7-year ARMs. With the 'Neutral Rate' firmly established, savvy buyers are using these products to secure the home now, betting on a moderate rate compression window in 2027 to move back into a 30-year fixed traditional product.
The Verdict
The California jumbo market is no longer the domain of the local branch manager. To succeed in the current May 2026 climate, buyers must look toward the 'shadow banking' sector. While the cost of capital is slightly higher, the flexibility offered by private credit is currently the only engine keeping the upper-middle and luxury tiers of California real estate moving forward.