The 2026 Credit Divide: Precision Pricing in a Stable Market
As of late April 2026, the California mortgage landscape has entered a phase of 'sticky stability.' Following the volatility of the mid-2020s, the 30-year fixed-rate mortgage has found a home in the 6.5% to 6.8% range. However, for California home buyers—particularly those in the high-cost coastal regions—the nominal rate is only half the story. A significant shift in Loan Level Price Adjustments (LLPAs) by the FHFA and private lenders has created a widening gap between 'prime' and 'super-prime' borrowers.
Current Rate Environment: April 2026
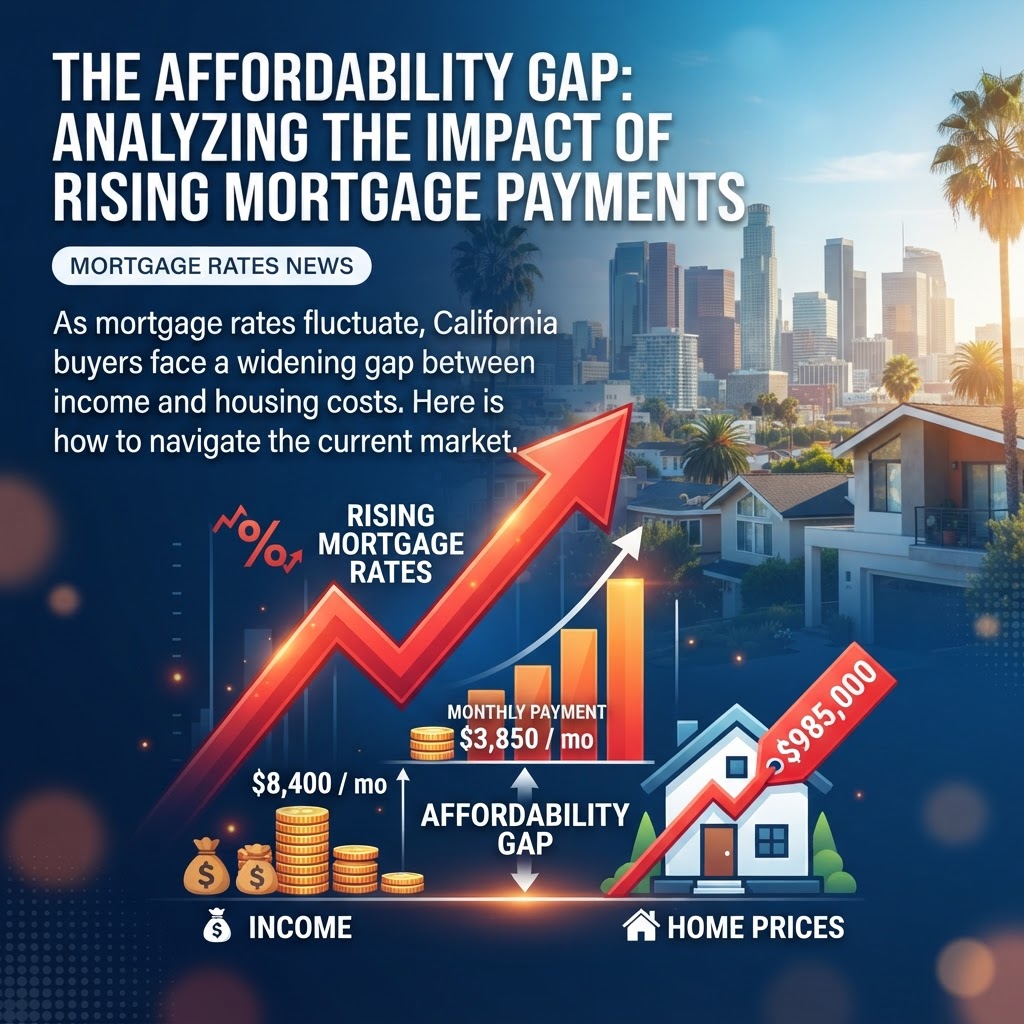
National averages are currently tracking at 6.62% for a 30-year fixed mortgage, while 15-year fixed terms are hovering at 5.95%. In California, where the median home price has climbed to approximately $895,000 according to recent California Association of Realtors (CAR) data, the prevalence of high-balance conforming loans means that small basis-point adjustments result in significant monthly payment variances.
The defining trend of this spring season is the '780 Threshold.' While a 740 credit score was historically the gold standard for top-tier execution, 2026 underwriting guidelines have shifted the most favorable pricing buckets to borrowers with FICO scores of 780 and above. For a typical $800,000 loan, the difference between a 740 and a 780 score can now represent a 0.25% to 0.375% difference in the locked interest rate.
The Impact on California’s High-Balance Market
California buyers are uniquely impacted by these tiered pricing structures due to the state’s reliance on high-balance conforming and jumbo products. In markets like the Bay Area and Orange County, where loan amounts frequently exceed $1.1 million, the 'credit-tier spread' can manifest as a $250 to $400 difference in the monthly mortgage payment.
Furthermore, current data from the Federal Reserve suggests that while inflation has been tamed to near 2.3%, the 'risk premium' on California real estate remains elevated due to inventory shortages. This has led lenders to tighten debt-to-income (DTI) requirements, often capping total obligations at 43% for those without significant cash reserves.
Strategic Takeaways for 2026 Buyers
- Target the 780 Bench: Prospective buyers should begin credit optimization at least six months prior to purchase. In the 2026 environment, moving from 'Very Good' to 'Exceptional' credit is the most effective way to lower a monthly payment, often more impactful than a larger down payment.
- The 15-Year Fixed Pivot: With the spread between 15-year and 30-year rates widening to nearly 70 basis points, more California move-up buyers are opting for shorter terms to circumvent the high-balance premiums associated with 30-year products.
- Front-End DTI Management: Lenders are increasingly scrutinizing revolving debt. Clearing high-interest credit card balances or deferred student loans before the application process is critical to qualifying for the highest possible loan amounts in a high-price-floor market.
Looking Ahead: The Summer Outlook
Economists at the NAR and major California brokerages expect rates to remain in this 'sideways' pattern through the summer of 2026. Without a significant catalyst from the Fed, the primary movement in the market will come from localized competition. For California buyers, the message is clear: in a world of 6.6% rates, your credit score is your most powerful negotiating tool.