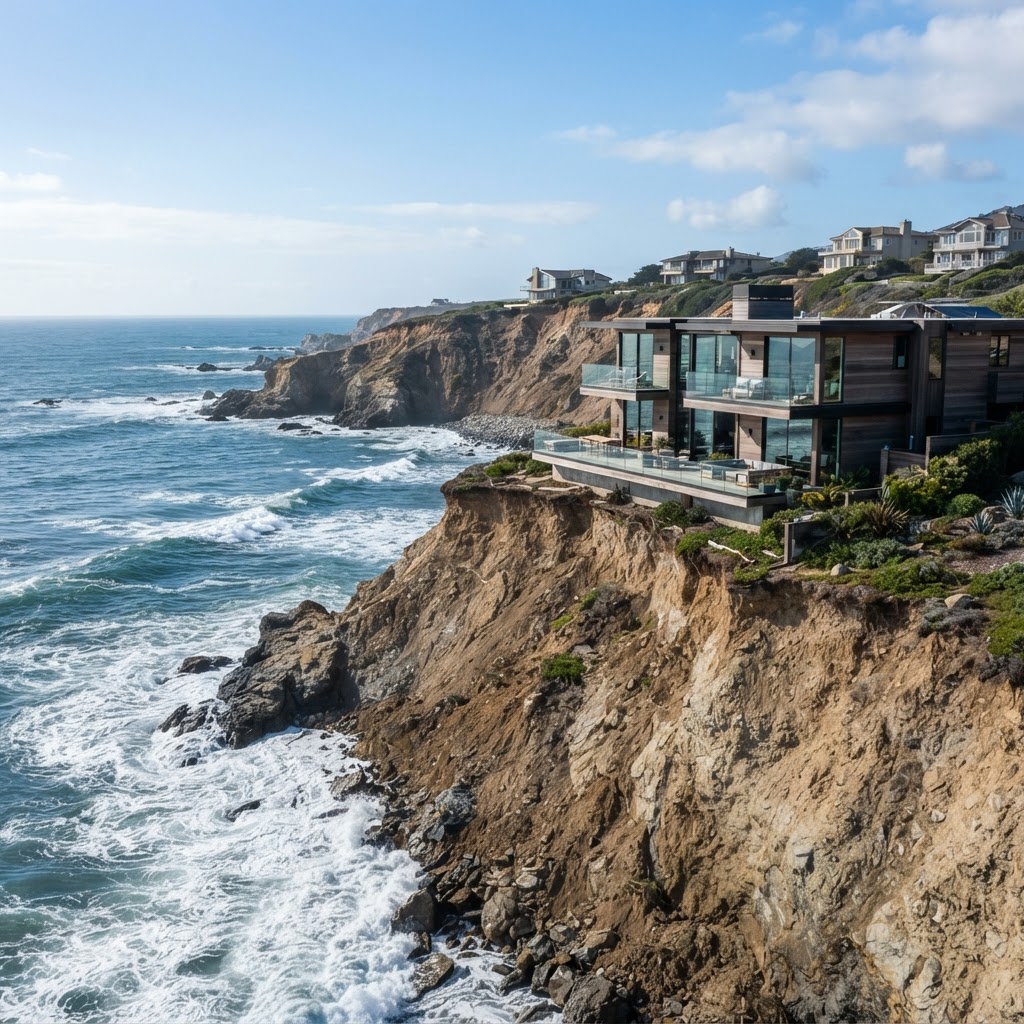
The Coastal Paradox: California Real Estate Faces Erosion and Price Divergence
As of October 2026, the California real estate landscape is defined by a stark dichotomy: the enduring allure of ultra-luxury zip codes versus the mounting physical and financial pressures on coastal properties. While market analysts have long focused on interest rate sensitivity, a new, more localized reality is taking hold across the Golden State.
The Coastal Risk Premium
The physical reality of California’s geography is increasingly impacting property valuations. Recent reports indicate that shoreline erosion is accelerating, particularly in Southern California, where highly developed coastal areas face severe long-term risks. This environmental shift is forcing a re-evaluation of "coastal premiums." Investors and homeowners are beginning to factor in the costs of mitigation and the potential for uninsurable losses, creating a subtle but growing hesitation in high-end coastal transactions that were previously considered bulletproof.
The Bay Area's Bifurcated Market
Despite broader economic headwinds, the Bay Area continues to defy national trends in specific pockets. Atherton has reclaimed its title as the nation’s most expensive zip code, with median home prices surpassing $10 million. However, this top-tier dominance masks a broader cooling trend. While San Francisco saw single-family home prices rise 17.4% year-over-year in September 2026, the market remains highly sensitive to inventory levels. In areas where inventory has tightened, such as San Mateo and Marin, competition remains fierce, with a significant majority of homes selling above list price.
Practical Takeaways for Market Participants
- For Investors: The "flight to quality" is no longer just about location; it is about climate resilience. Properties with significant erosion exposure may face higher insurance premiums and lower long-term liquidity. Conduct thorough due diligence on local coastal management plans before committing to high-value acquisitions.
- For Buyers: The market is highly localized. While national headlines may suggest a softening, "seller's market" conditions persist in supply-constrained pockets like San Francisco. Buyers should prioritize neighborhoods with low inventory turnover, as these areas are showing the most price resilience despite the 6.86% average 30-year fixed mortgage rate.
- For Sellers: In markets with rising inventory, such as parts of the Inland Empire, price reductions are becoming a standard tool to maintain momentum. Sellers in these regions should be prepared for longer days-on-market and should focus on competitive pricing strategies early in the listing cycle to avoid stagnation.
As we move into the final quarter of 2026, the California market is proving that it is not a monolith. Success in this environment requires moving beyond state-level averages and focusing on the micro-trends—whether that is the specific erosion risk of a coastal parcel or the inventory-driven competition of a dense urban neighborhood.


