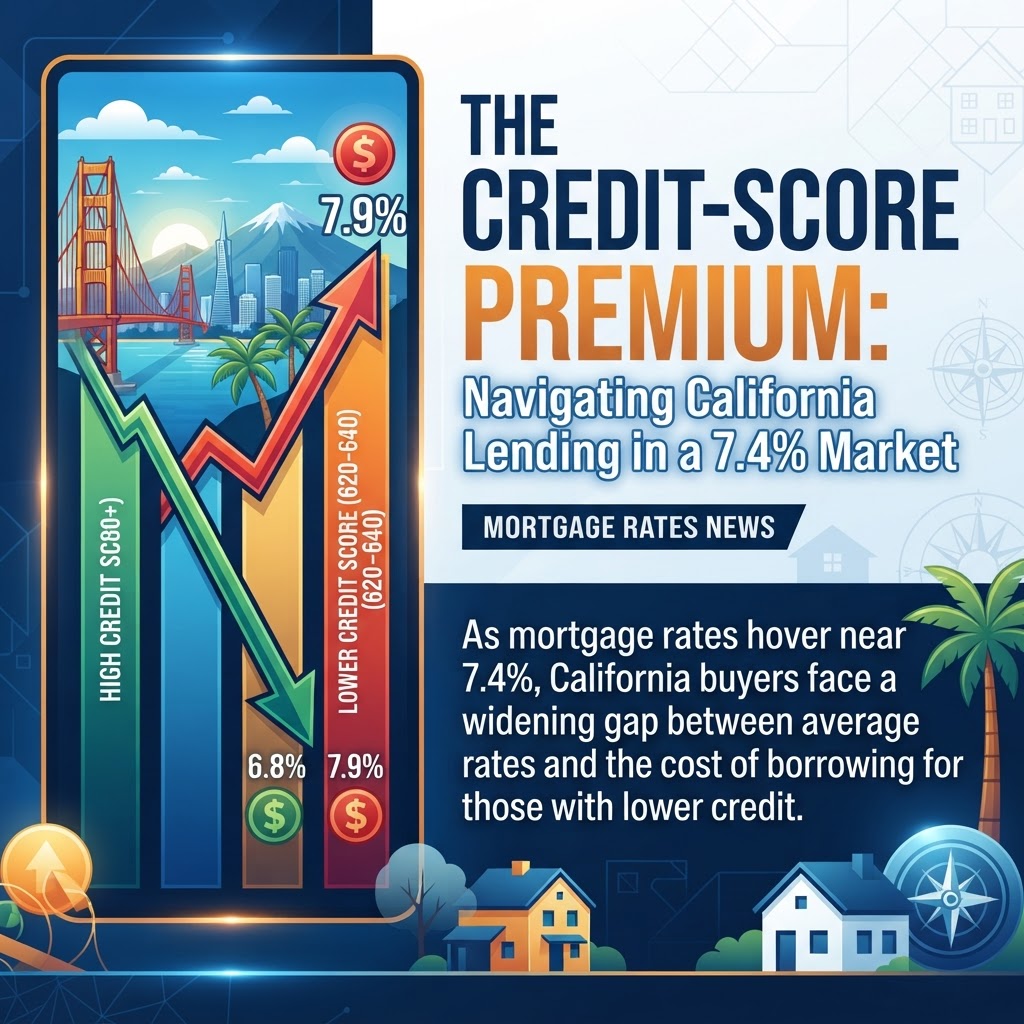
The Credit-Score Premium: Navigating California Lending in a 7.4% Market
As of mid-October 2026, the national average for a 30-year fixed-rate mortgage has stabilized near 7.36% to 7.45% [2, 5]. For California home buyers, this environment represents more than just a high-interest hurdle; it marks a fundamental shift in how lenders evaluate risk, creating a pronounced 'credit-score premium' that is reshaping the state's housing market.
The Widening Gap in Borrowing Costs
While national averages provide a baseline, the reality for California borrowers is increasingly bifurcated. With inflation data remaining stubborn throughout 2026, lenders have tightened underwriting standards [4, 5]. Data from the Mortgage Bankers Association indicates that total application volume has fallen by 4.2% recently, reflecting a cooling demand as buyers grapple with these elevated costs [6, 10]. In high-cost markets like California, where loan amounts often exceed conforming limits, the spread between 'prime' borrowers and those with mid-tier credit scores has widened significantly.
Strategic Implications for California Buyers
The current lending environment demands a shift in strategy for those looking to enter the market:
- Prioritize Credit Optimization: In a 7.4% environment, the difference between a 720 and a 780 credit score can translate to thousands of dollars in annual interest payments. Buyers should focus on debt-to-income (DTI) ratio reduction before applying.
- The Down Payment Lever: With lenders risk-averse, larger down payments are no longer just about reducing monthly principal; they are essential tools for securing more favorable interest rate tiers.
- Focus on Total APR: As noted in recent market data, the APR often reflects fees that can be overlooked [2]. California buyers should demand a full breakdown of closing costs to understand the true cost of capital, rather than focusing solely on the advertised interest rate.
Market Outlook
The Federal Reserve’s decision to maintain higher benchmark rates throughout 2026 has effectively ended the era of 'easy' financing [4, 7]. For California, this means the inventory of homes may remain constrained as current homeowners with sub-4% rates are disincentivized to sell. Prospective buyers must prepare for a market where competition is lower, but the cost of entry is higher, necessitating a more disciplined approach to financial preparation and loan shopping.
Practical Takeaway
If you are planning a purchase in the coming quarter, treat your credit report as a financial asset. Even a marginal improvement in your score can help you bypass the most punitive pricing tiers currently being applied by lenders in response to the broader economic uncertainty.


