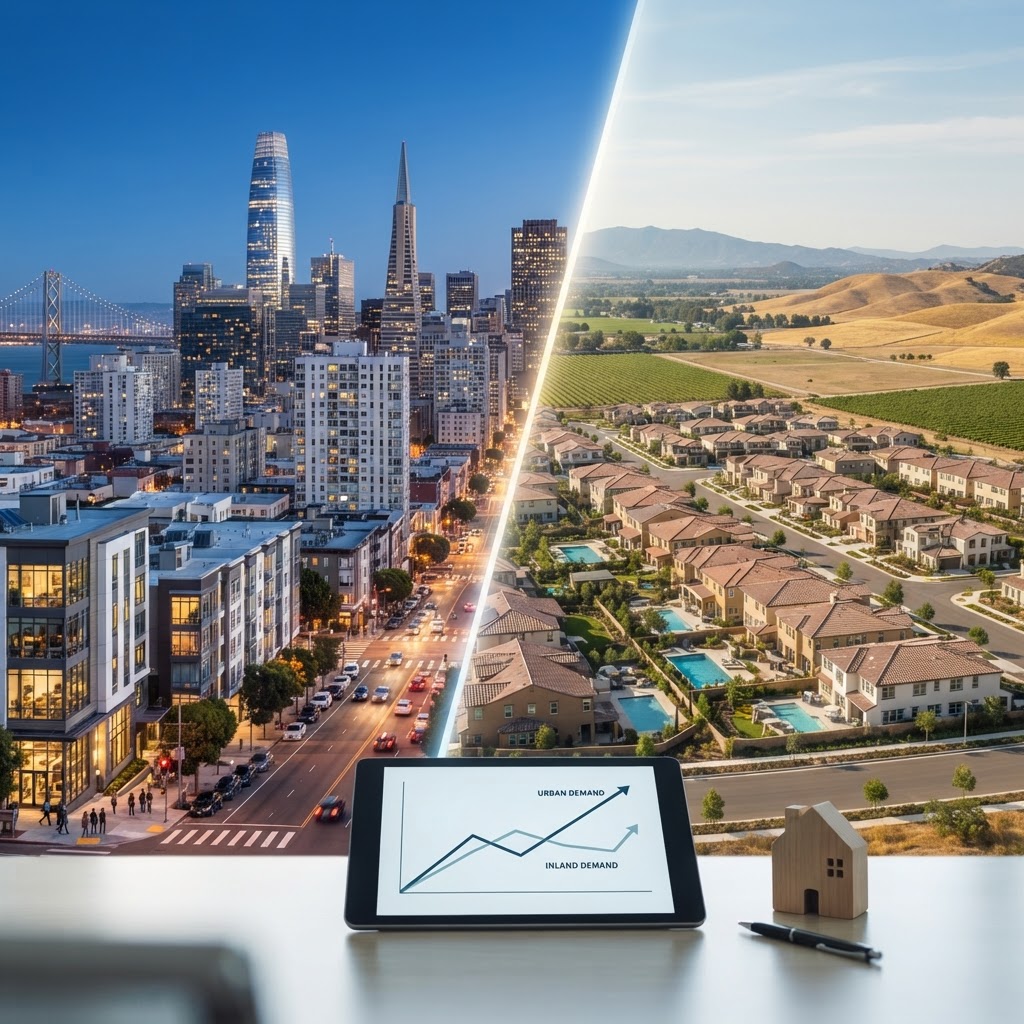
The Bifurcated Market: Analyzing California’s 2026 Urban-Inland Divergence
As we move through the second half of 2026, the California real estate landscape has moved beyond the broad-brush narratives of the early decade. Instead, the market is defined by a sharp divergence between high-density urban centers and the state's inland corridors. Understanding this split is essential for investors and homeowners looking to navigate the current equilibrium.
The Urban Rental Correction
In major metropolitan hubs like Los Angeles, the narrative has shifted toward supply absorption. With significant new multi-family inventory hitting the market—such as the 5,100 units recently added in Downtown Los Angeles—vacancy rates have climbed to approximately 5.6% to 5.7% [3]. For the first time in years, this has forced landlords in Class A properties to offer concessions to attract tenants, signaling a temporary cooling in urban rental growth.
Inland Resilience and the Supply Constraint
Conversely, the broader statewide market remains anchored by a persistent, structural supply shortage. While the statewide median home price saw a slight correction from its May 2026 peak of $930,260 to $904,640 in June, it remains 0.4% higher year-over-year [3]. The fundamental issue remains the pace of new construction; California’s permitting volume continues to lag significantly behind states like Texas and Florida, ensuring that demand consistently outstrips supply in most residential sub-markets [2].
Investment Perspectives: Where to Look
Investors should note that the "one-size-fits-all" approach to California real estate is no longer viable. Key takeaways for the current market include:
- Monitor Urban Concessions: In dense urban cores, the current influx of new supply provides a window for renters and a challenge for investors. Focus on properties with unique amenities that can withstand competitive pressure.
- Inland Stability: Markets with limited land availability and slower construction pipelines continue to show price resilience. These areas remain less susceptible to the vacancy spikes seen in downtown metro zones.
- The Affordability Gap: With the state homeownership rate at 55.5%—well below the national average of 65.1%—the demand for entry-level housing remains a long-term tailwind for investors who can provide attainable housing solutions [2].
Economic Context
The underlying economic indicators remain supportive of a stable, if expensive, market. California’s GDP growth of 1.3% and job growth of 0.9% have outperformed initial 2026 projections [2]. While high acquisition costs remain a barrier, the combination of a strong labor market and a constrained housing pipeline suggests that the "high-cost equilibrium" is likely to persist through the remainder of the year.


