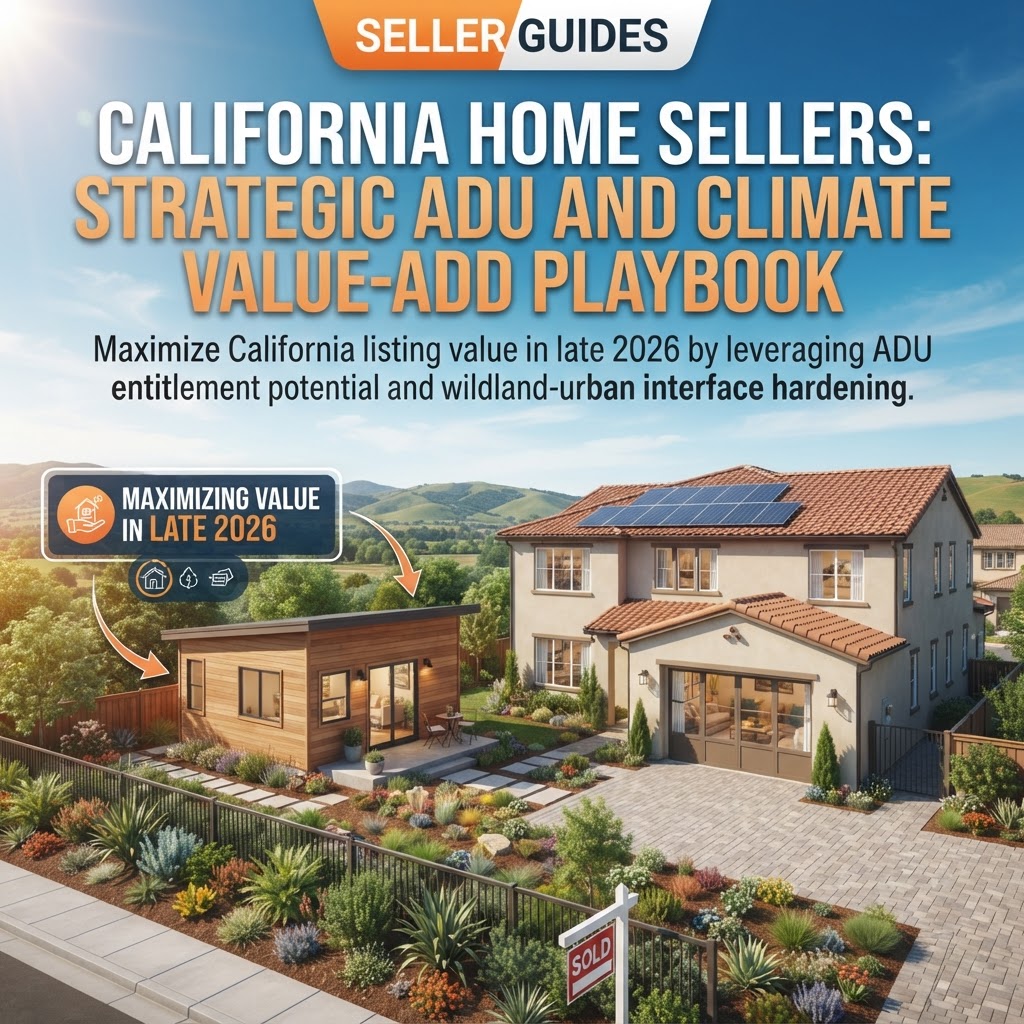
Targeting the Modern Golden State Premium
California’s housing landscape has matured into a nuanced, bifurcated ecosystem. As statewide median home values hover around $914,810 and statewide inventory balances near 3.4 months of supply, sellers can no longer rely on unguided appreciation to secure multiple bids. Instead, winning over today’s cost-sensitive buyers—only 18% of whom can comfortably purchase a median-priced home in California—requires positioning properties around two vital criteria: revenue-generation capacity and climate resilience.
With 36.6% of California listings still securing above-list outcomes according to Redfin market metrics, premium valuations belong to properties that actively address persistent homeowner pain points: soaring property insurance premiums and housing affordability.
1. Unlock the ADU Value Multiplier
Accessory Dwelling Units (ADUs) and junior ADUs have transformed from peripheral novelties into core appraisal drivers across California. For single-family sellers, even if building an ADU before listing is not feasible, delivering an "ADU-ready" property creates immense financial upside for buyers seeking mortgage offset potential or multigenerational living.
- Permit & Feasibility Packets: Provide prospective buyers with a pre-vetted zoning feasibility report citing California state ADU regulations. Document utility capacity, setbacks, and sewer lateral status.
- Sub-Panel and Trenching Readiness: If upgrading service panels during pre-sale prep, opt for a 200-amp electrical main panel. Highlighting sub-panel capacity for a future detached structure immediately flags the home as a turnkey expansion opportunity.
- Permitted Conversion Marketing: If your home features an existing garage conversion, ensure all paperwork aligns with city records. Fully permitted ADUs deliver substantially higher square-footage valuations compared to non-permitted conversions.
2. Hardening and Insurability as Core Sales Strategy
Property insurance availability has become a defining bottleneck in California escrows. Listings in high-fire severity zones or Wildland-Urban Interface (WUI) perimeters frequently stall or fall out of contract over insurance availability. Sellers who proactively "harden" their real estate directly protect transaction certainty.
- Defensible Space Compliance: Fully document compliance with California Public Resources Code 4291. Maintain a clean Zone 0 (0–5 feet from the structure) by removing combustible mulch, dead vegetation, and wood fences touching the building.
- Ember-Resistant Retrofits: Replace standard attic and foundation vents with 1/8-inch ember-resistant models. These modest hardware upgrades present low overhead but serve as major value additions during buyer underwriting.
- Pre-Secured Coverage Portfolios: Coordinate with an insurance broker prior to listing to assemble an insurability disclosure folder, confirming quotes or coverage options (including surplus lines or California FAIR Plan compatibility) to assure skittish buyers that escrow will close on schedule.
3. Tax-Smart Preparation and Equity Realization
Planning for California capital gains requires granular preparation. Because California treats capital gains as ordinary income with state tax rates reaching up to 13.3%, sellers must structure their cost basis documentation early.
- Capital Improvement Tracking: Gather receipts for capital improvements executed throughout your ownership—ranging from new roofing to plumbing overhauls—to increase your adjusted basis against Section 121 limits ($250,000 for individual filers, $500,000 for married couples).
- FTB Withholding Exemptions: Familiarize yourself with California Franchise Tax Board (FTB) Form 593. Escrow is mandated to withhold 3 1/3% of the gross sale price unless a qualified exemption applies, such as principal residence qualification.
Actionable Seller Checklist for Late 2026
- Audit Utility Infrastructure: Verify sewer lateral compliance and upgrade electrical panels to accommodate dual-metering or ADU expansions.
- Execute Zone 0 Landscaping: Clear all combustible materials within 5 feet of structural perimeters to preserve buyer insurance eligibility.
- Compile an Entitlement Dossier: Map lot setbacks, easement footprints, and city zoning allowances directly in your marketing collateral to attract high-intent investors and multigenerational buyers.


