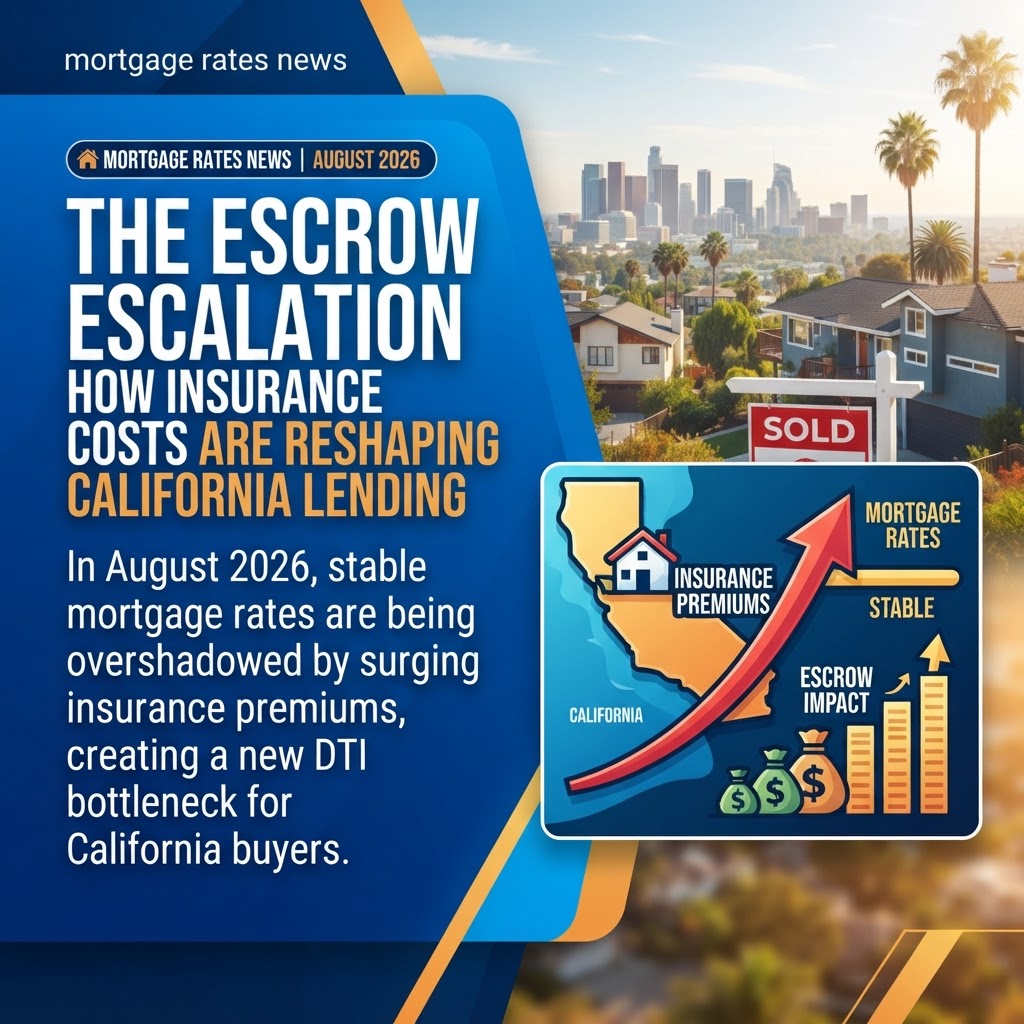
The Shift from Interest Rates to Total PITI
As of August 2, 2026, the California mortgage landscape is witnessing a curious phenomenon. While the 30-year fixed-rate mortgage has found a steady rhythm between 5.85% and 6.1%—a relief after the volatility of early summer—a new variable is threatening loan approvals across the Golden State. The cost of the 'I' in PITI (Principal, Interest, Taxes, and Insurance) is now a primary driver of loan denials and downsized purchasing power.
The DTI Crunch: A New Mathematical Reality
Lenders typically cap a borrower's Debt-to-Income (DTI) ratio at 43% to 50%, depending on the loan product. In 2024 and 2025, the primary threat to this ratio was the interest rate. However, according to recent data from the California Association of Realtors (CAR), homeowners insurance premiums in high-fire-risk zones and even suburban coastal pockets have increased by 35% to 50% year-over-year. For a median-priced California home of $900,000, an insurance jump from $2,500 to $6,000 per year adds nearly $300 to the monthly payment—the equivalent of a 0.4% increase in the mortgage rate.
The 'Insurance Contingency' Emerges
Lending news in August reveals that underwriters are now scrutinizing insurance quotes earlier in the process. Previously, insurance was a 'check-the-box' item near closing. In the current market, California lenders are increasingly requiring a preliminary insurance binder or a FAIR Plan quote before issuing a formal loan commitment. This shift is designed to prevent 'fallen escrows' where a buyer qualifies for the rate but fails the final DTI audit due to a high insurance premium.
Key Data Points for August 2026:
- Average 30-Year Fixed: 5.95% for 740+ FICO borrowers.
- Insurance Impact: Average annual premiums in California now represent 0.8% to 1.2% of the home's value in Tier 2 fire zones.
- DTI Failure Rate: Approximately 12% of California loan applications in July were restructured specifically due to escrow cost increases.
Practical Takeaways for California Stakeholders
For Buyers:
Do not rely on the 'estimated' insurance cost provided by automated mortgage calculators. In the current California market, you must obtain a specific insurance quote for the property address before removing your loan contingency. If a private carrier will not cover the property, calculate the cost of a California FAIR Plan policy combined with a 'Difference in Conditions' (DIC) wrap, as this will likely be your highest-cost scenario.
For Sellers:
To keep your deal on track, provide a history of your current insurance premiums and any fire hardening upgrades (such as vent screens or defensible space clearing) to prospective buyers. Transparency regarding the 'insurability' of the home is becoming as vital as the home inspection itself.
For Investors:
The yield compression seen in early August is being driven as much by non-interest expenses as by the rates themselves. When analyzing California portfolios, the 'Net Operating Income' (NOI) calculation must now account for a more aggressive insurance escalation clause to ensure long-term debt service coverage ratios (DSCR) remain viable.
Conclusion
While the 'August Anchor' of stabilized rates provides a foundation for the market, the California lending environment is no longer just about the cost of money. It is about the cost of protection. Buyers who successfully navigate the next 30 days will be those who treat insurance as a primary financial pillar rather than a closing-day afterthought.


