The Great Geographic Equalization: Yield Over Appreciation
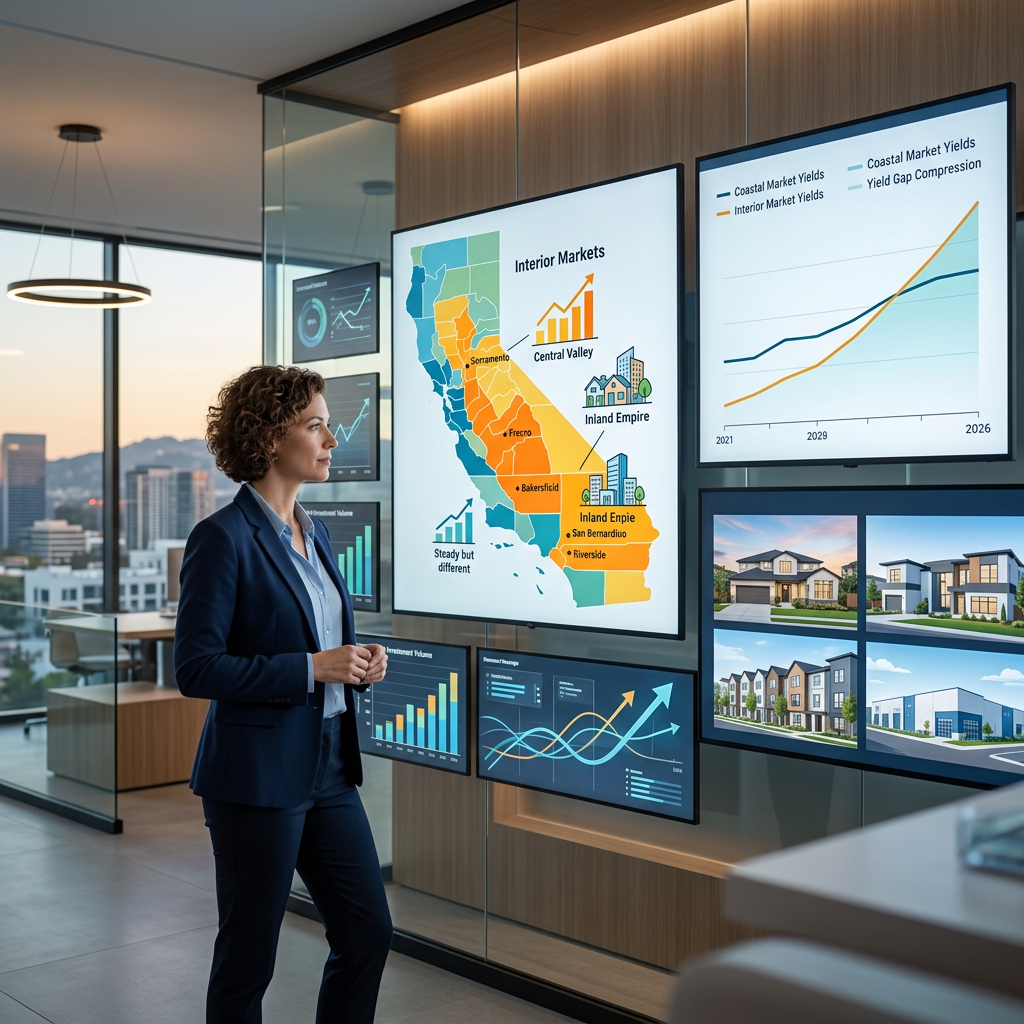
As we enter the second quarter of 2026, the California real estate landscape is witnessing a profound structural shift. For decades, the ‘California Play’ was synonymous with coastal appreciation. However, a new economic reality has taken hold. The ‘Yield Gap Compression’—a phenomenon where the return on investment (ROI) in secondary markets is rapidly outpacing traditional coastal hubs—is now the primary driver of capital migration within the Golden State.
According to recent data from the California Association of Realtors (CAR) and CBRE, the cap rate spread between the Bay Area and the Central Valley has narrowed significantly. While San Francisco and Los Angeles residential assets are averaging cap rates of 3.1% to 3.4%, markets like Fresno, Bakersfield, and the Inland Empire are seeing stabilized yields between 5.6% and 6.1%. This 250-basis-point delta is attracting a new wave of institutional and private capital that is no longer satisfied with the ‘buy and hold for equity’ strategy of the early 2020s.
The Central Valley’s Institutional Inflexion
The narrative of the Central Valley as a ‘budget alternative’ is officially over. In 2026, it has become a primary target for institutional Build-to-Rent (BTR) developers. Census Bureau data from late 2025 indicates that net domestic migration into the San Joaquin Valley has increased by 14% year-over-year, driven by remote-work permanence and the search for a lower cost of living.
Investment firms are pivoting. Blackstone and Starwood-affiliated entities have increased their acquisition targets in the Sacramento-Roseville-Folsom corridor by 22% this year alone. They are betting on the ‘Equity Migration’—homeowners from the coast selling high-value properties and relocating to the interior with significant cash reserves, creating a robust, high-credit-score tenant pool that didn't exist in these regions five years ago.
Infrastructure as a Value Multiplier
The 2026 surge in interior value is not merely speculative; it is grounded in infrastructure. The progress on the High-Speed Rail segments in the Central Valley and the completion of major logistics hubs in Riverside and San Bernardino have created a ‘jobs-housing’ synergy that was previously lacking. MLS data shows that properties within a 15-mile radius of new logistics and transit nodes in the Inland Empire have seen a 9% price premium over the state average, even as coastal markets remain flat.
Practical Takeaways for 2026 Stakeholders
For those navigating the current market, the following strategic pivots are recommended:
- For Investors: Focus on ‘Secondary Hub’ multifamily assets. The risk-adjusted return in markets like Clovis or Ontario currently exceeds that of Class-A coastal assets. Look for value-add opportunities in 1990s-era builds that can be modernized to capture the high-income migrant demographic.
- For Sellers: If you are holding coastal property, 2026 represents a peak liquidity window. With the ‘Inventory Thaw’ in full effect, buyers are active, but the window for 1031 exchanges into higher-yield interior properties is narrowing as prices in those markets climb.
- For Buyers: Look beyond the commute. The value in 2026 is found in ‘Connected Hubs’—areas with high-speed internet infrastructure and proximity to regional airports, rather than just highway proximity to coastal CBDs.
The Economic Outlook
As the Federal Reserve maintains a ‘higher-for-longer’ stance on the neutral rate, the cost of capital remains a headwind. However, California’s interior markets are proving resilient because their price-to-income ratios remain far more sustainable than those in the coastal metros. By the end of 2026, we expect the Inland Empire and Central Valley to lead the state in total transaction volume, marking a permanent shift in the state’s economic center of gravity.


