The New Gatekeeper: Insurability
In the spring 2026 California market, the traditional checklist of 'fresh paint and staged furniture' has been superseded by a more critical factor: the ability to secure an affordable insurance policy. As the California Department of Insurance continues to navigate the 'Sustainable Insurance Strategy' implemented in 2025, sellers are finding that properties without a clear path to coverage are languishing on the market, regardless of their aesthetic appeal. In high-risk regions, the primary question from buyers has shifted from 'How old is the roof?' to 'Can I get a quote?'
The Insurance-Ready Listing Strategy
Data from the 2025 California Association of Realtors (CAR) Annual Report indicates that 18% of transactions in high-fire-risk zones faced delays or cancellations due to insurance hurdles. To mitigate this, savvy sellers are now preparing an 'Insurance Binder' as part of their pre-listing package. This document includes a preliminary quote from at least one carrier or a verified eligibility statement for the California FAIR Plan. By removing the insurance unknown, sellers decrease the buyer's risk profile and minimize the likelihood of a deal falling through during the contingency period.
AB 38 Compliance: Beyond Disclosure
While Assembly Bill 38 requires sellers of properties in high fire hazard zones to disclose fire hardening features, the 2026 market demands more than just paperwork. Sellers who proactively complete 'low-cost' retrofits—such as replacing standard 1/4-inch mesh vents with 1/16-inch ember-resistant vents—are seeing a distinct 'Resilience Premium.' According to recent MLS trends, homes with documented fire-hardening upgrades and a completed Cal Fire defensible space inspection sell on average 4.2% faster than non-compliant properties in similar zip codes.
Practical Takeaways for Sellers
- Commission a Resilience Audit: Before listing, hire a professional to assess defensible space and structural vulnerabilities. This proactive step allows you to fix issues before they appear on a buyer’s home inspection.
- Pre-Clearance Quotes: Work with an independent broker to identify carriers currently writing in your zip code. Providing a list of 'insurable paths' to prospective buyers can be as valuable as a kitchen upgrade.
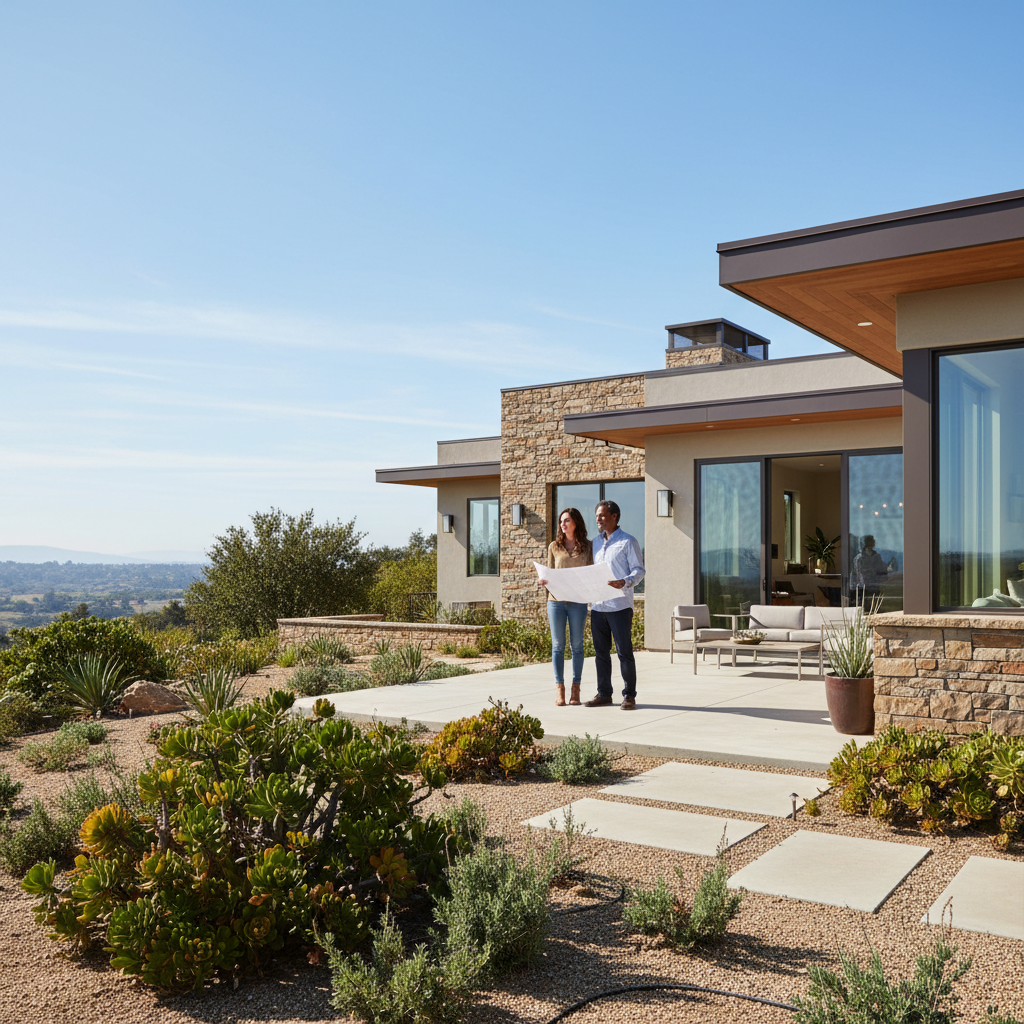
- Focus on 'Hard' Curb Appeal: Replace flammable bark mulch with river rock or gravel and ensure a five-foot non-combustible zone around the entire perimeter of the home.
- Water Conservation Synergy: Use drought-tolerant, fire-resistant succulents and native plants to meet both environmental mandates and fire safety goals.
By shifting the focus from cosmetic luxury to structural resilience, California sellers can reassure nervous buyers and ensure that insurance availability does not become a deal-breaker in the final stages of escrow.


