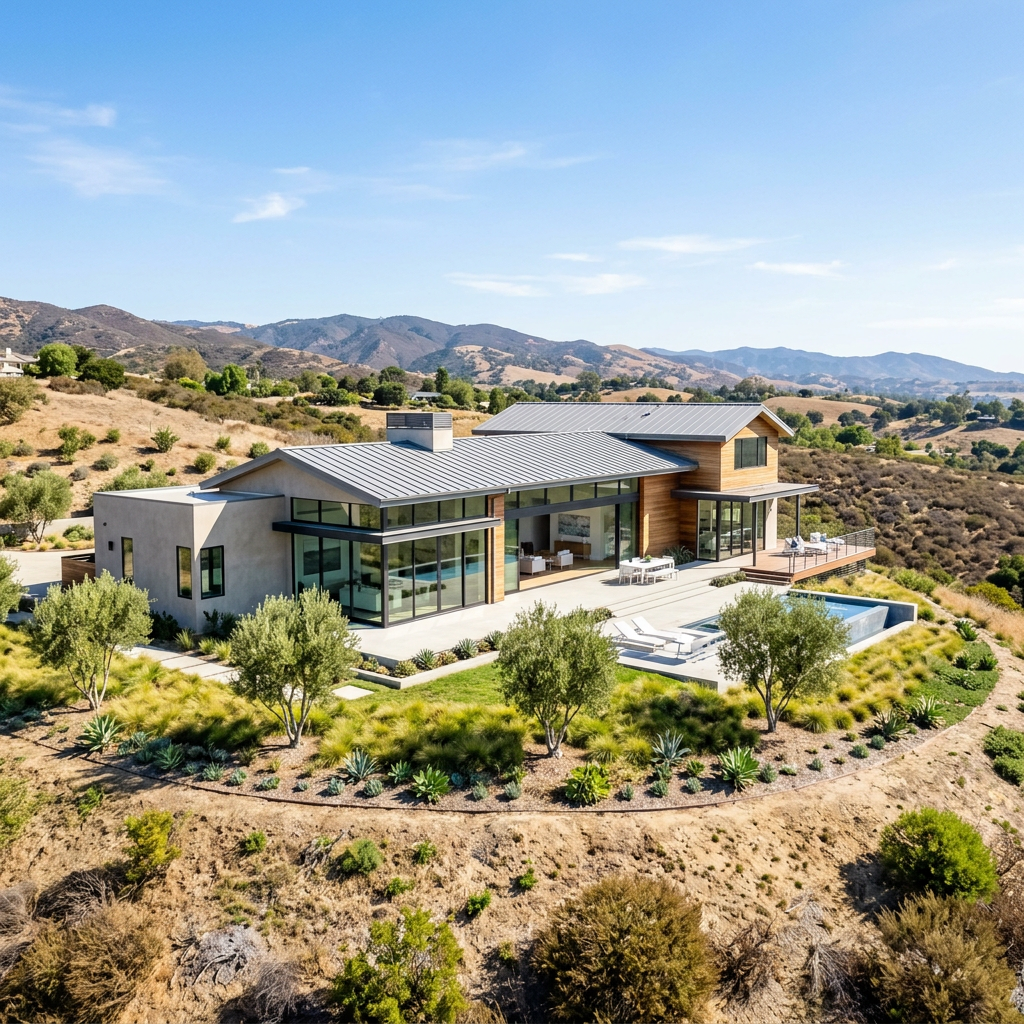
The New Reality: Insurance as a Financing Contingency
As of March 2026, the California housing market has shifted from price-discovery to risk-discovery. Following the full implementation of the California Department of Insurance (CDI) Sustainable Insurance Strategy in late 2025, buyers are navigating a landscape where the availability of a policy is no longer guaranteed. For the 2026 buyer, the 'Insurance Contingency' is now as vital as the appraisal. According to recent data from the California Association of Realtors (CAR), nearly 18% of failed escrows in the previous quarter were attributed to the buyer’s inability to secure affordable fire coverage.
The CDI Sustainable Insurance Strategy and Your Premium
By early 2026, major carriers like State Farm and Allstate have begun reintegrating into the CA market, but under strict conditions. The 'Sustainable Insurance Strategy' allows insurers to use forward-looking catastrophe modeling rather than historical data. While this has increased the availability of policies, it has also led to tiered pricing based on a property’s specific 'Fire Risk Score.' Buyers must now verify if a property falls within a Wildland-Urban Interface (WUI) zone before making an offer, as these zones carry premiums that can impact a debt-to-income (DTI) ratio by as much as 3% to 5%.
Navigating the California FAIR Plan in 2026
For properties in high-risk zones where private options remain scarce, the California FAIR Plan remains the insurer of last resort. In 2026, the FAIR Plan has seen expanded coverage limits, but it requires a 'Difference in Conditions' (DIC) wrap-around policy to cover theft, liability, and water damage. Buyers should be aware that FAIR Plan inspections are now more rigorous; failing to meet 'defensible space' requirements within 30 days of closing can lead to immediate policy cancellation, triggering a technical default on most conventional and FHA loans.
The AB 38 Compliance Factor
California Assembly Bill 38 requirements are now a standard hurdle in 2026. Sellers in high fire-hazard severity zones must provide documentation of home hardening and defensible space compliance. Practical buyers should look for upgrades such as 1/16th-inch ember-resistant vents, non-combustible gutter guards, and double-paned tempered glass. Properties lacking these features not only face higher insurance premiums but may also require a 'withhold' of funds in escrow to ensure remediation, a negotiation point that is becoming standard in the 2026 purchase agreement.
Practical Takeaways for the 2026 Buyer
- The 72-Hour Rule: Do not wait for the 17-day contingency period. Submit the property address to an insurance broker within 72 hours of an accepted offer to get a preliminary quote and a CLUE (Comprehensive Loss Underwriting Exchange) report.
- Verify 'Hardened Home' Credits: Ask the seller for proof of fire-hardening retrofits. Many 2026 insurance products offer a 10-15% premium discount for properties meeting specific CDI-approved mitigation standards.
- Budget for the DIC Wrap: If a home requires the FAIR Plan, budget an additional $1,500 to $2,500 annually for the necessary DIC wrap-around policy to ensure full coverage equivalent to an HO-3 policy.
- Analyze the NHD Report Early: The Natural Hazard Disclosure (NHD) is your most important document. Review the 'Fire Risk' and 'VHFHSZ' (Very High Fire Hazard Severity Zone) designations immediately to determine if the property is eligible for preferred-tier pricing.


