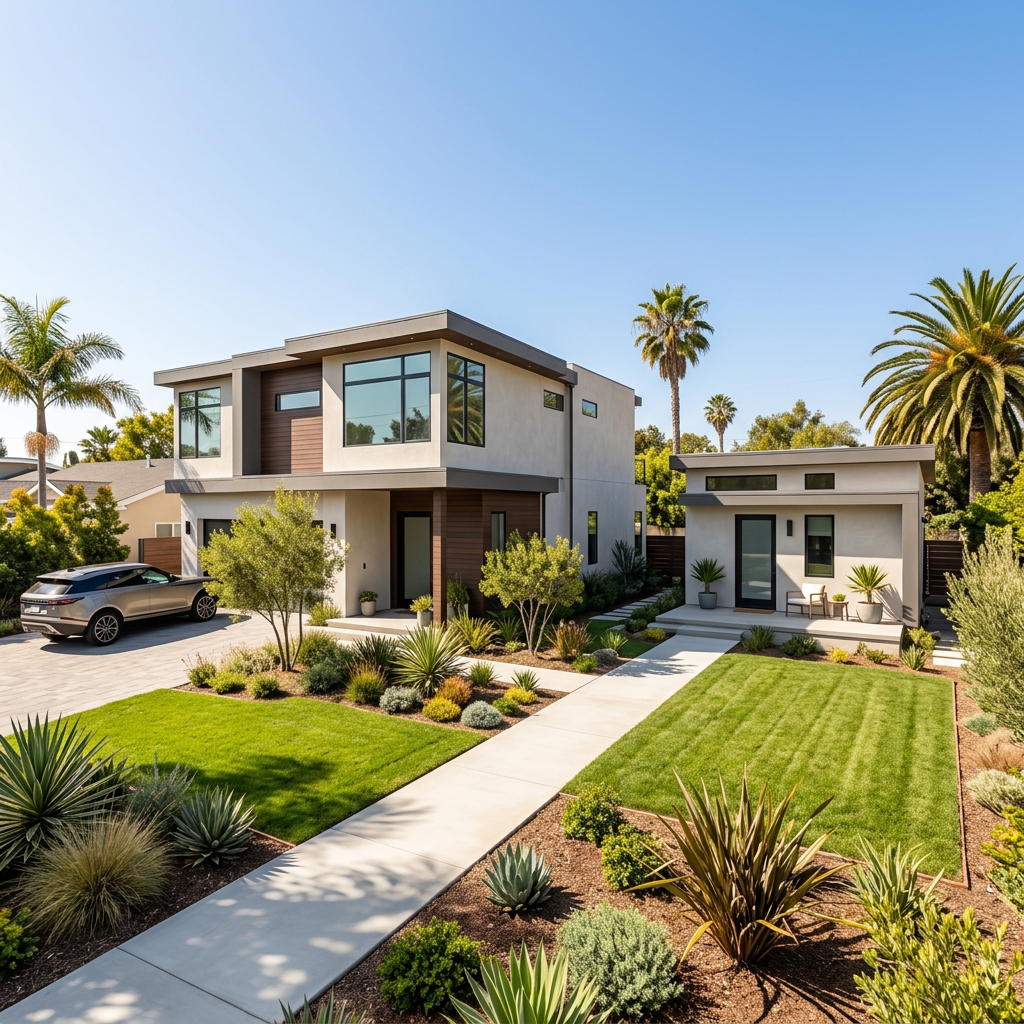
The 2026 California Landscape: Data-Driven Market Realities
As of March 2026, the California real estate market continues to be defined by high demand and constrained supply. According to recent data from the California Association of Realtors (CAR), the median home price has hovered near $860,000, while the Housing Affordability Index indicates that only 17% of California households can comfortably afford a median-priced home. To succeed in this environment, buyers must look beyond simple aesthetic preferences and focus on legislative advantages and long-term utility.
The ADU Income Offset Strategy
One of the most significant shifts in California real estate over the last few years has been the expansion of Accessory Dwelling Unit (ADU) rights. Under recent state mandates, almost all single-family lots are entitled to at least one ADU and one Junior ADU. Practical Takeaway: Buyers should prioritize properties with existing ADUs or sufficient lot space to build one. In high-cost areas like Los Angeles or the Bay Area, a secondary unit can generate between $1,800 and $3,500 in monthly rental income, effectively subsidizing a mortgage and increasing the buyer's debt-to-income (DTI) flexibility during the underwriting process.
Prop 19 and the 'Empty Nester' Inventory
Proposition 19 has fundamentally changed the inventory pipeline in California. By allowing homeowners over 55, or those with severe disabilities, to transfer their property tax basis to a new primary residence up to three times, more 'move-down' inventory is entering the market. Actionable Insight: Work with an agent to identify long-term owners who are utilizing Prop 19. These sellers are often more motivated to close quickly because their tax incentives are tied to the purchase of their next home, providing savvy buyers with more leverage in negotiations.
The Insurance and Disclosure Hurdle
In 2026, the Natural Hazard Disclosure (NHD) report is as important as the home inspection. With many major insurers limiting new policies in high-fire-threat districts, securing affordable coverage has become a primary contingency. Practical Steps: Before removing your inspection contingency, obtain a formal insurance quote. In California, the 'Fair Plan' serves as a last resort, but its high premiums can drastically alter your monthly carrying costs. Always verify if a property is within a High Fire Hazard Severity Zone (HFHSZ) early in the due diligence phase.
Strategic Financing in a Stable Rate Environment
With mortgage rates stabilized around 5.8%, the 2026 buyer is no longer waiting for a 'crash' that historical Census data suggests is unlikely due to extreme supply deficits. Instead, buyers are utilizing 'buydown' programs where sellers credit 2% to 3% of the purchase price to temporarily lower the buyer's interest rate. This tactic is often more effective for monthly cash flow than a simple reduction in the sales price.


